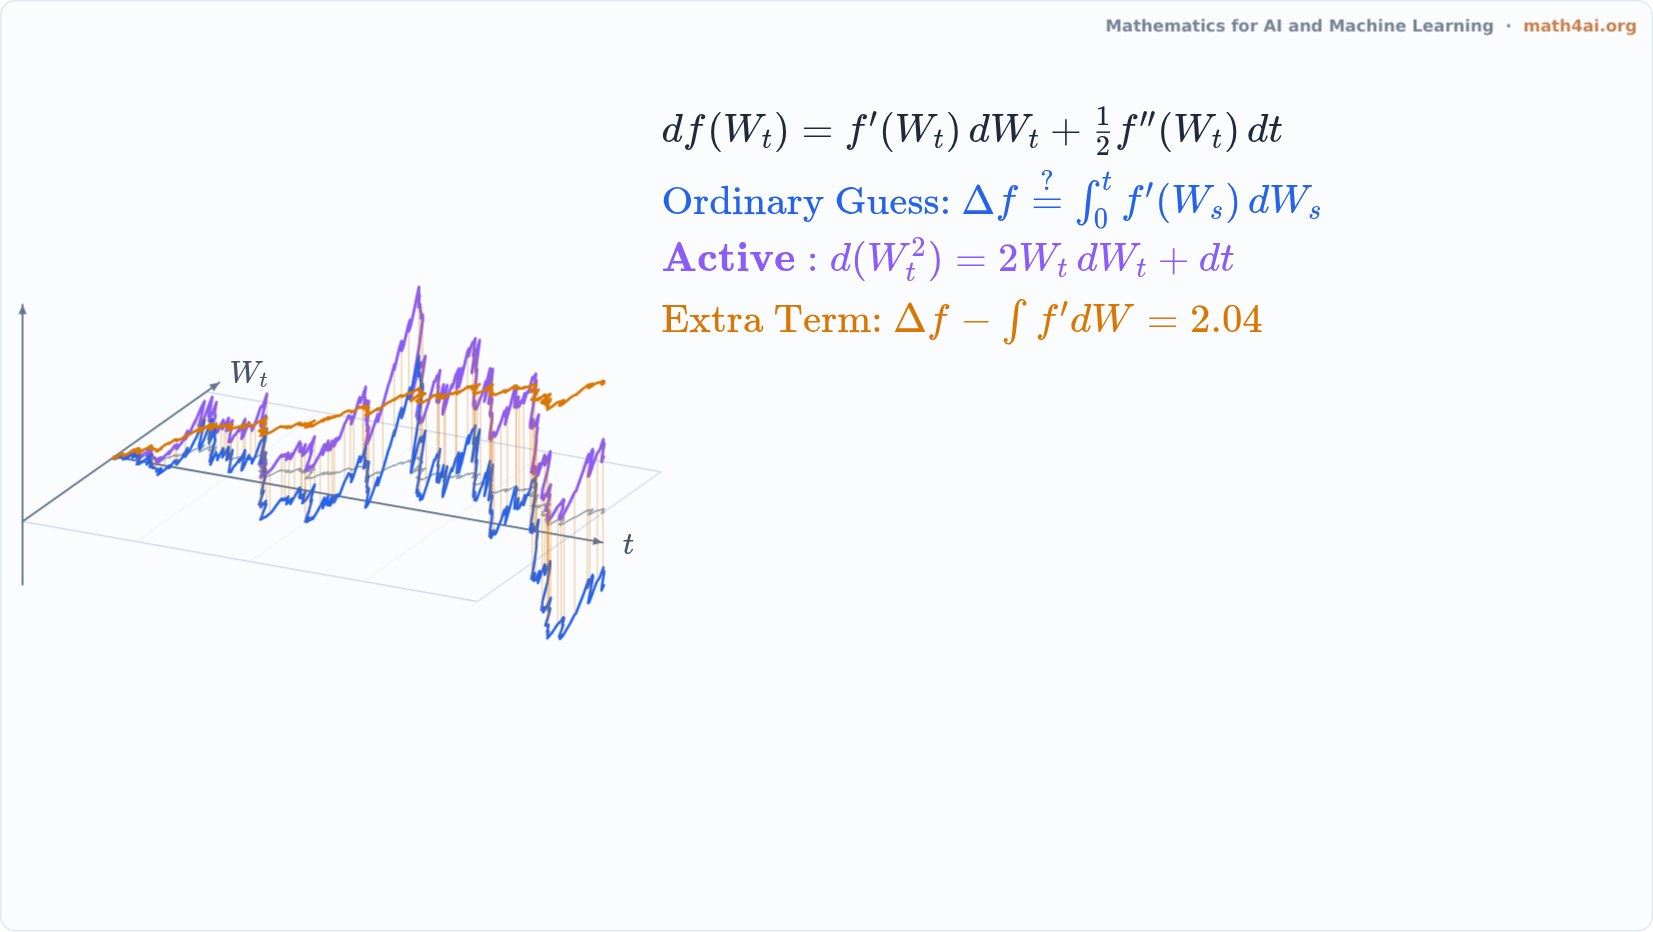
Itô's Lemma: The Extra Second-Order Drift
An interactive live film: f(W_t) - f(0) vs the first-order stochastic integral, with the discrepancy perfectly tracked by the accumulated curvature drift (1/2) f''(W_s) dt.
Narration
In ordinary calculus, the differential of f of x is f prime of x times d x. But when x is a Brownian motion, its quadratic variation is non zero, and ordinary calculus fails.
Ito's lemma expands f to second order. Because d W squared equals d t, the second derivative term does not vanish. It adds a deterministic drift of half f double prime d t.
The rest of the narration is in the book's Companion.
More from Chapter 19
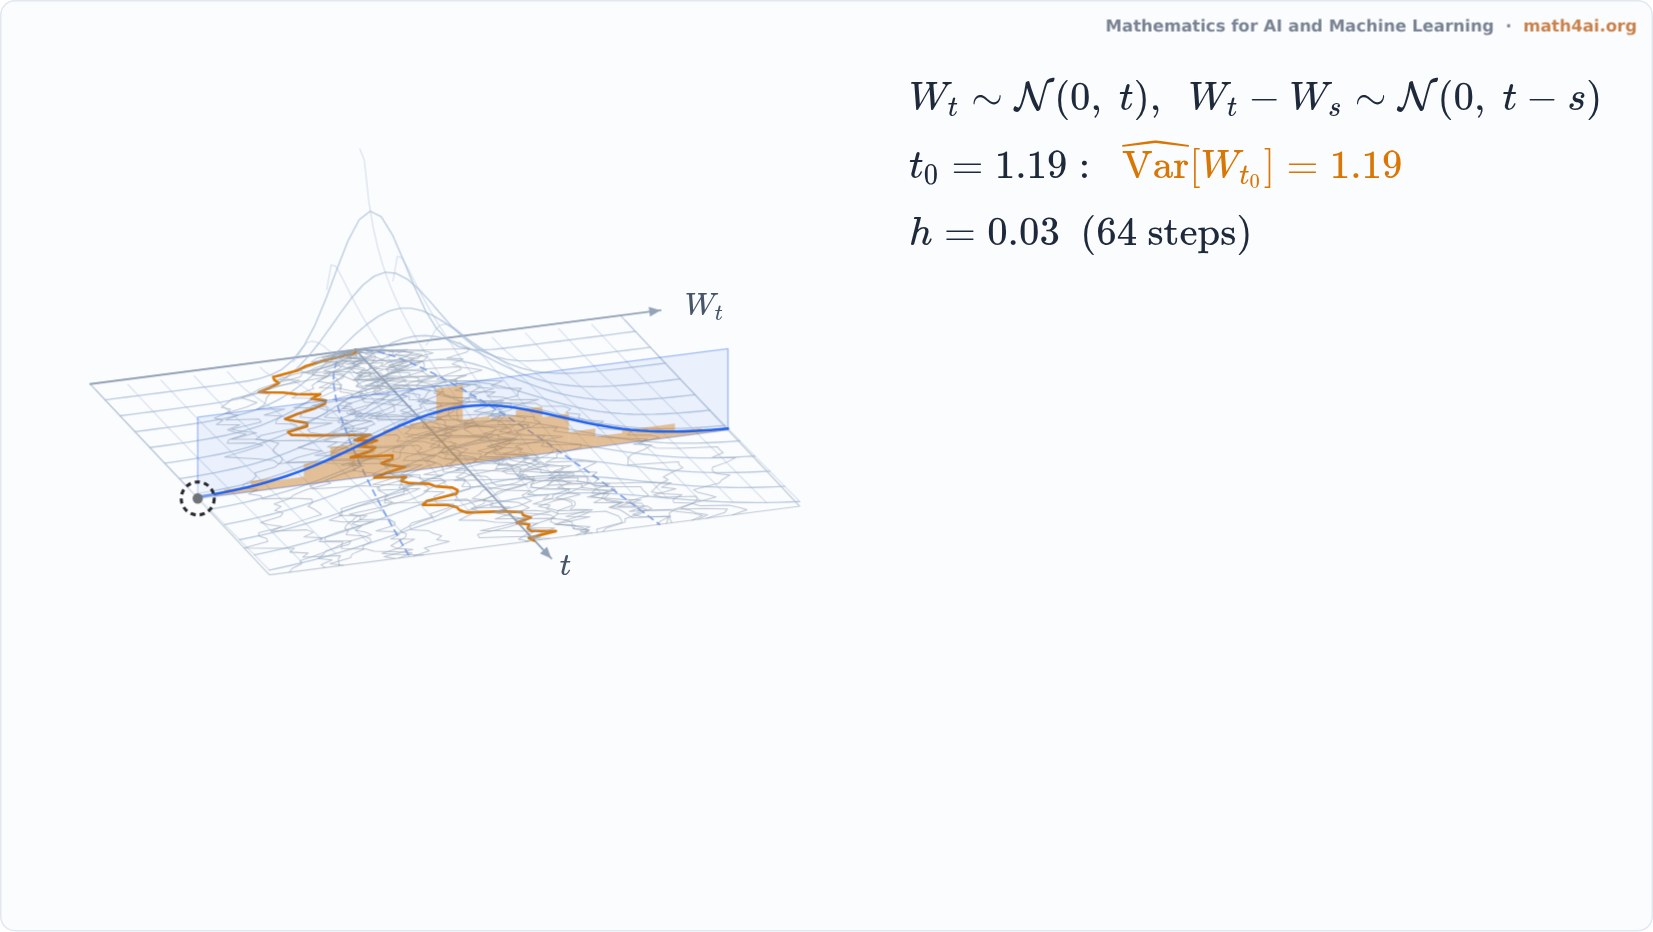 Interactive1:37Brownian Motion: Rough Paths, a Spreading Bell, and dW Squared Equals dtChapter 19
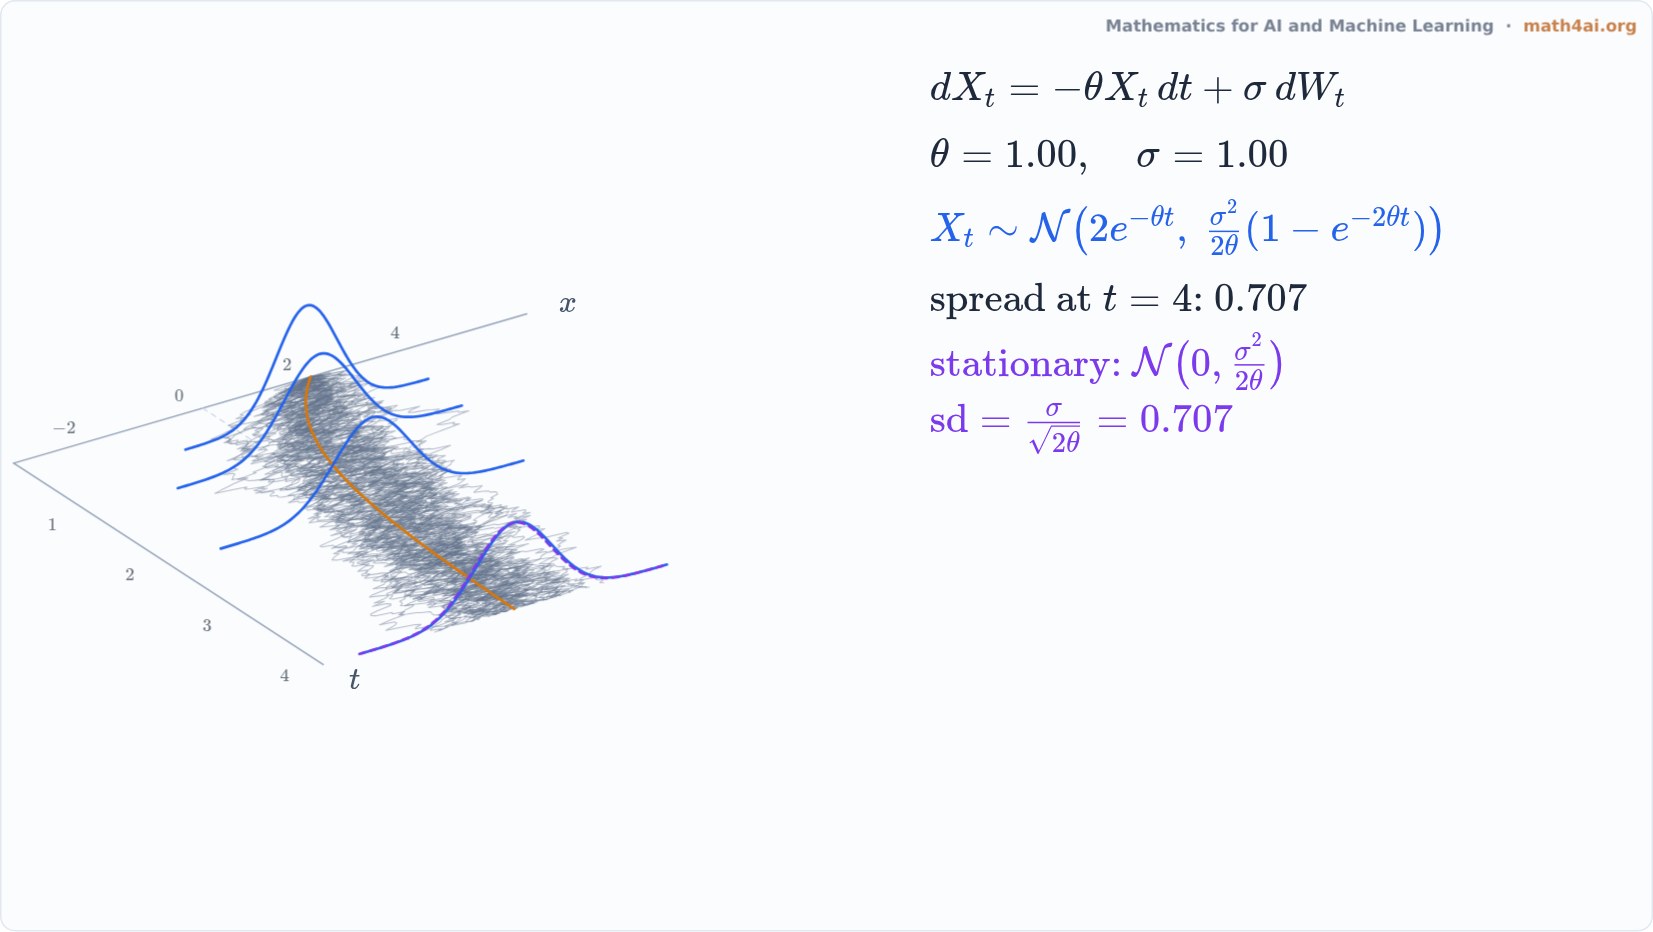 Preview1:17The Ornstein-Uhlenbeck Process: Brownian Motion on a SpringChapter 19
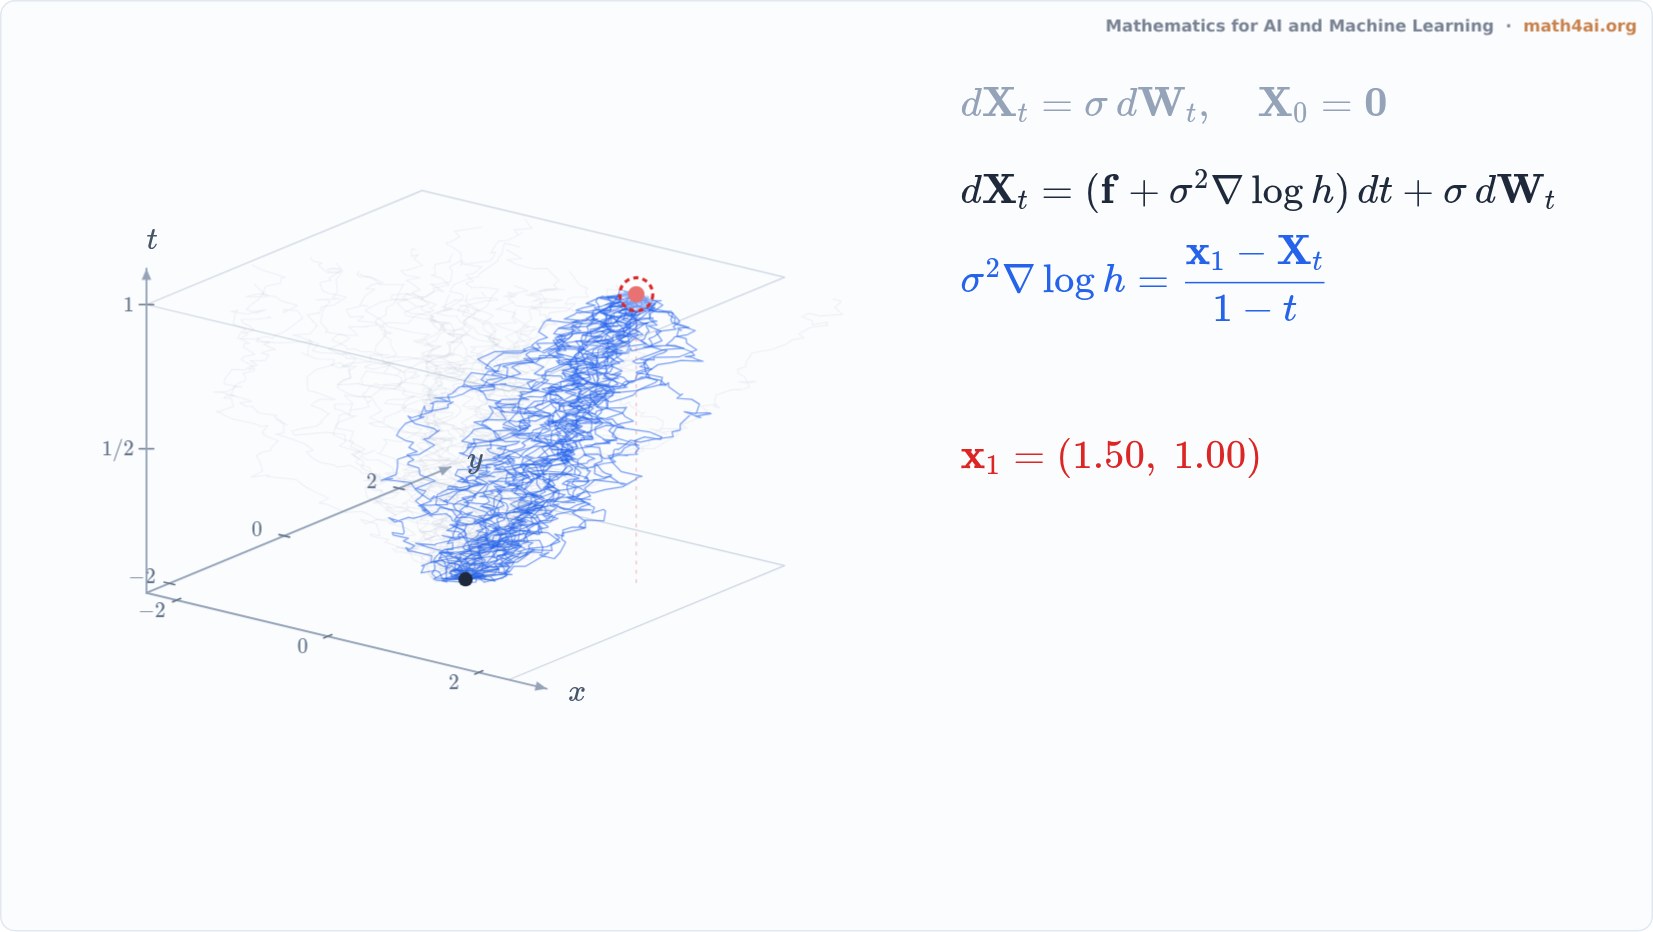 Preview1:29Conditioning a Diffusion on Its EndpointChapter 19
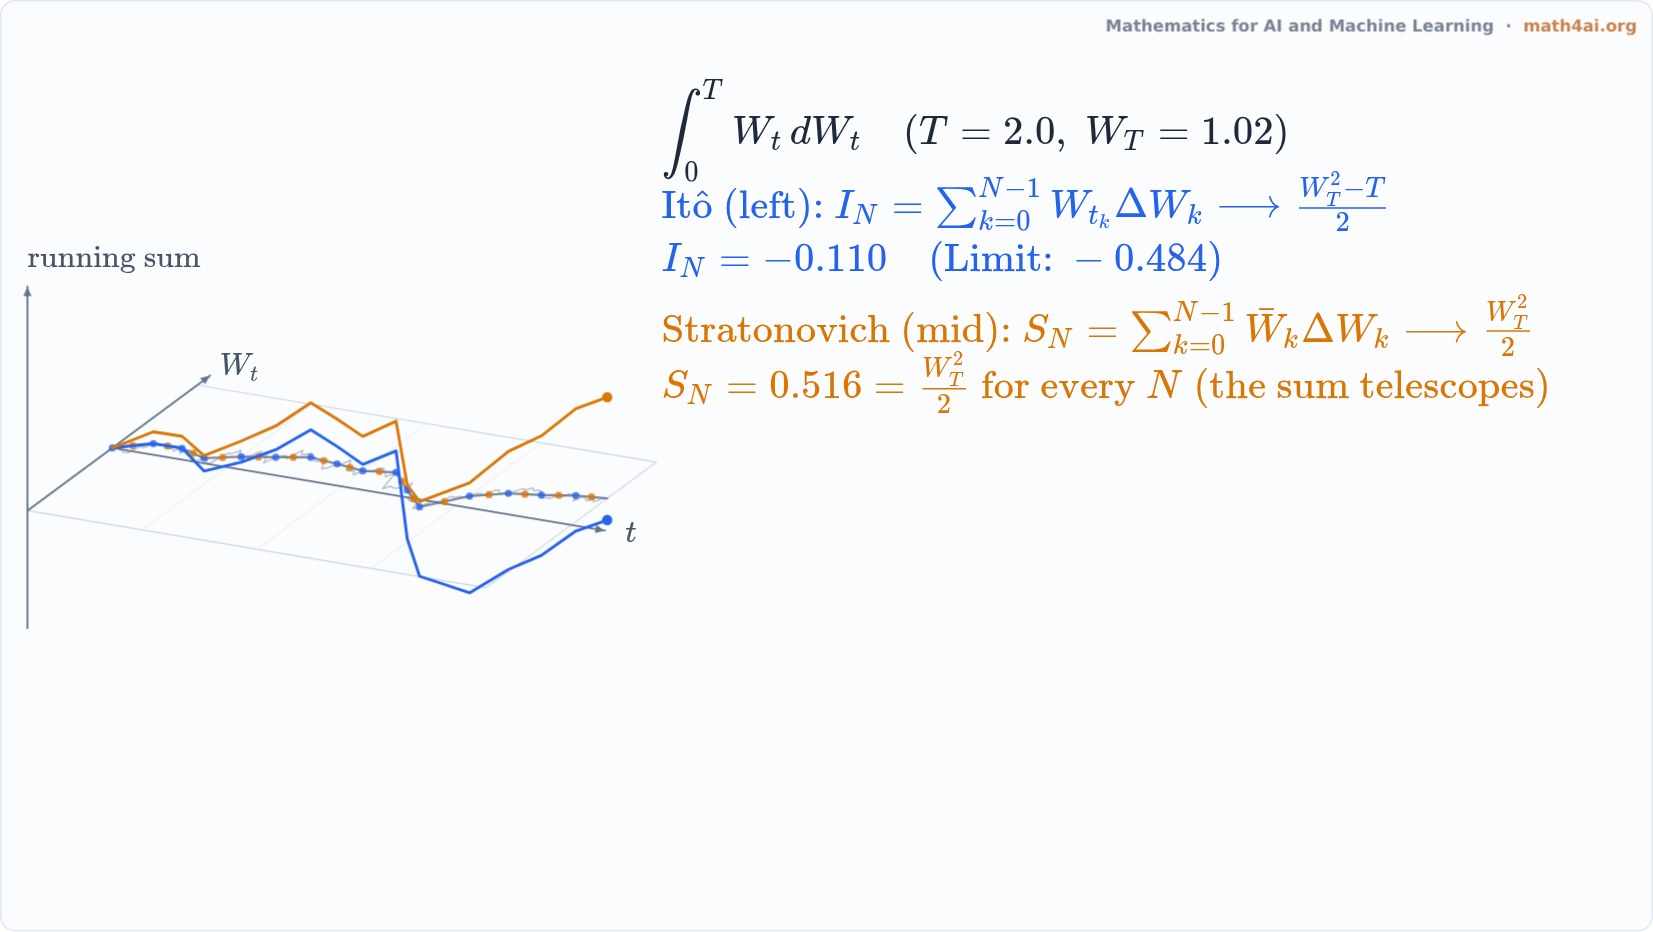 Preview1:46Itô vs Stratonovich: Left Endpoint or MidpointChapter 19
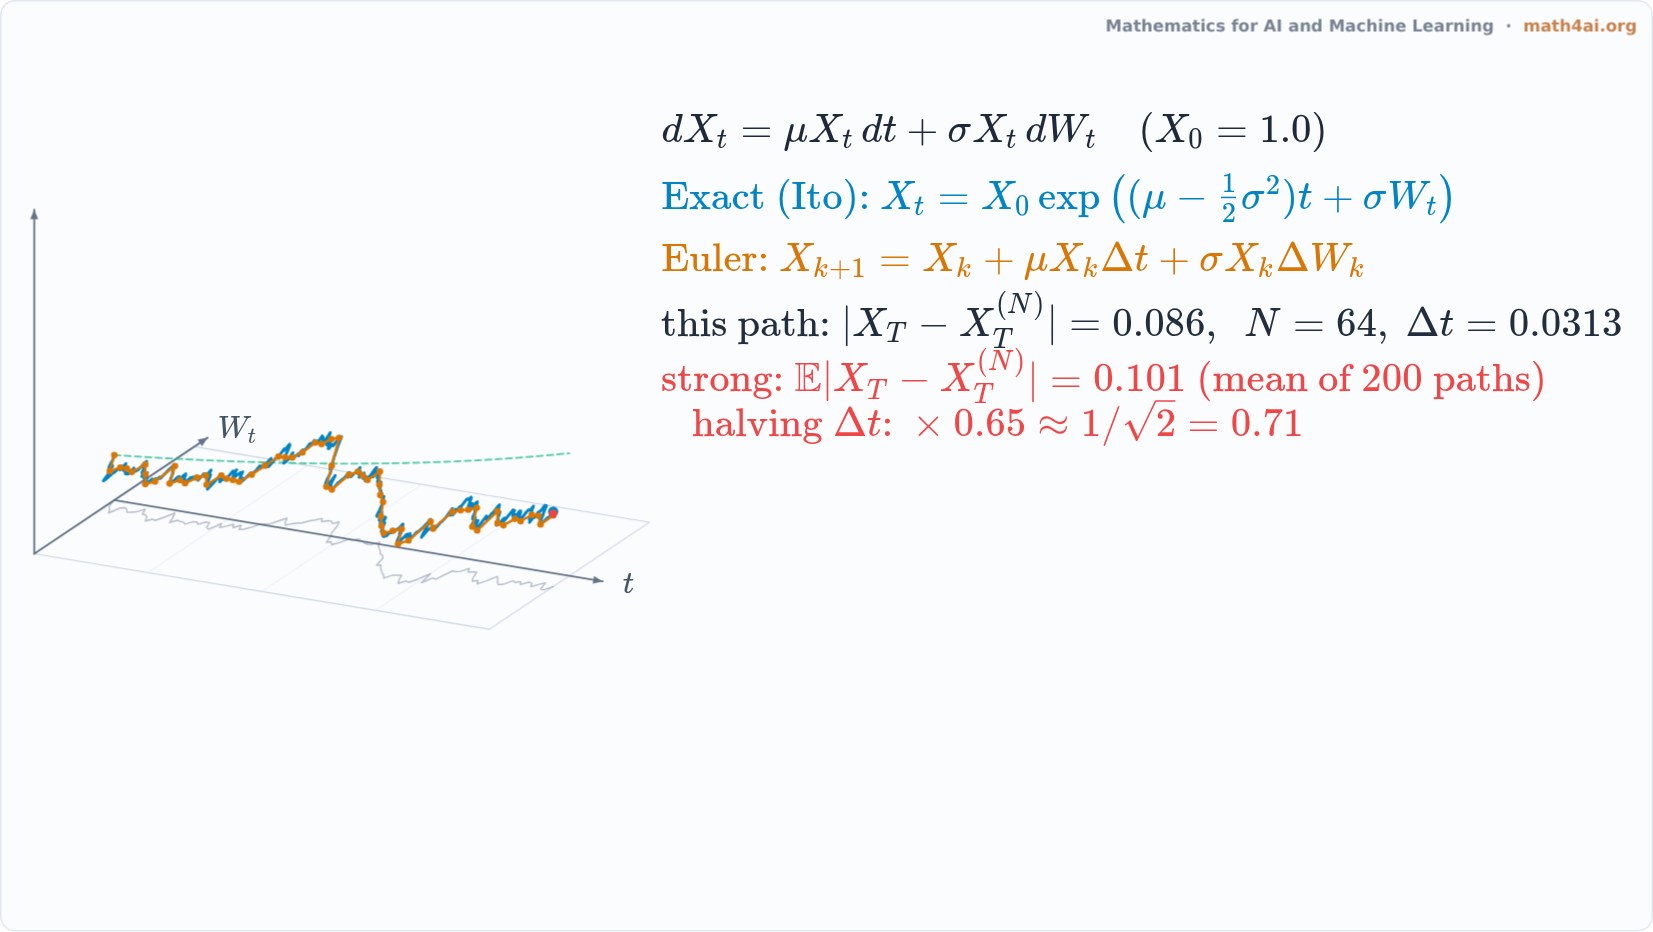 Preview1:56Euler–Maruyama: SDEs as Limits of AlgorithmsChapter 19