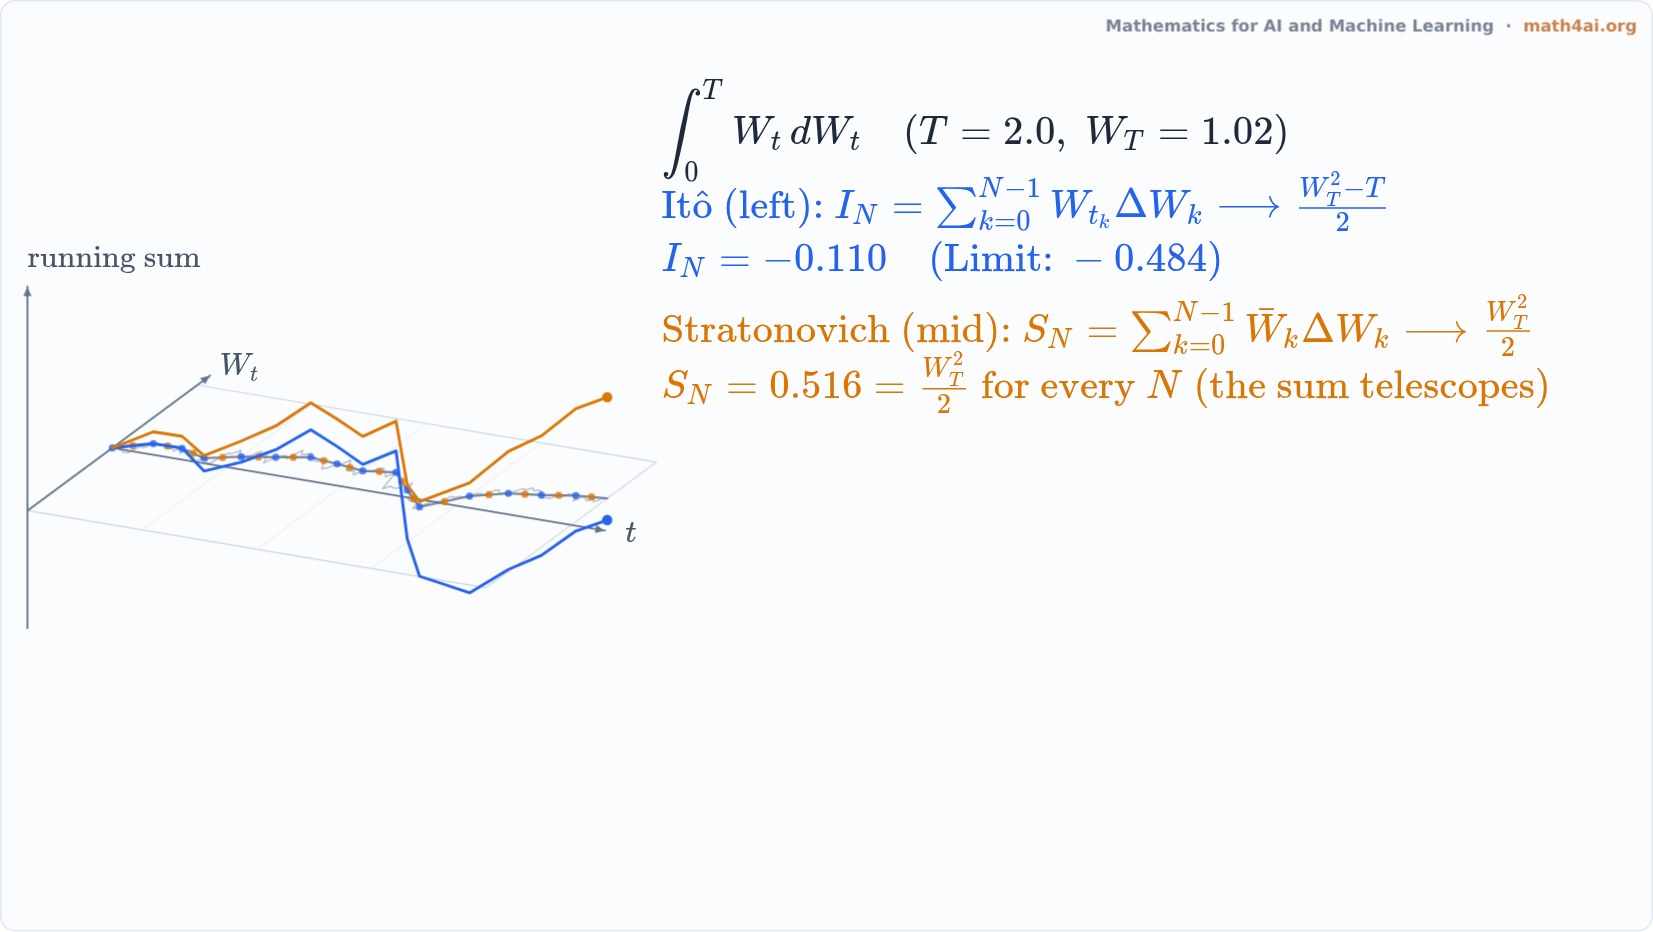
Itô vs Stratonovich: Left Endpoint or Midpoint
An interactive live film: two stochastic Riemann sums on the same Brownian path; left endpoint converges to (W_T^2 - T)/2, midpoint converges to W_T^2 / 2, with the gap T/2 emerging from (dW)^2 = dt.
Narration
The stochastic integral of W d W looks familiar, but Brownian motion is nowhere differentiable. The Riemann sum depends on where inside each time step we evaluate the integrand.
The Ito integral evaluates the path at the left endpoint of each interval. It never looks ahead. As the partition refines, this left sum converges to half of W at capital T squared minus capital T.
The rest of the narration is in the book's Companion.
More from Chapter 19
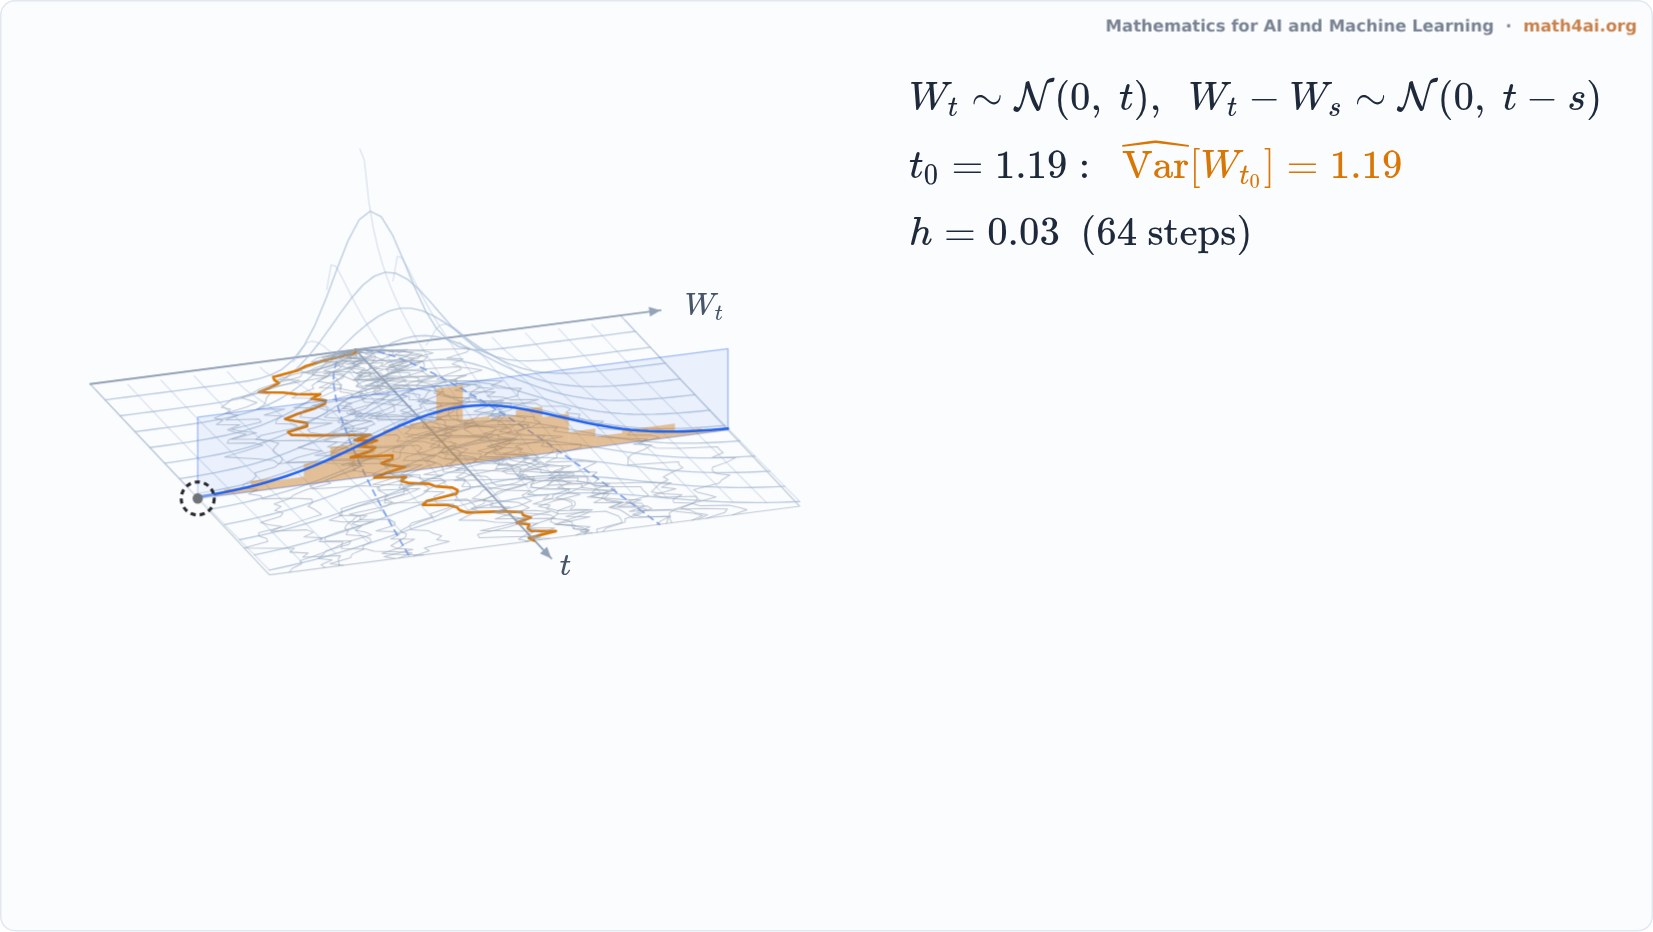 Interactive1:37Brownian Motion: Rough Paths, a Spreading Bell, and dW Squared Equals dtChapter 19
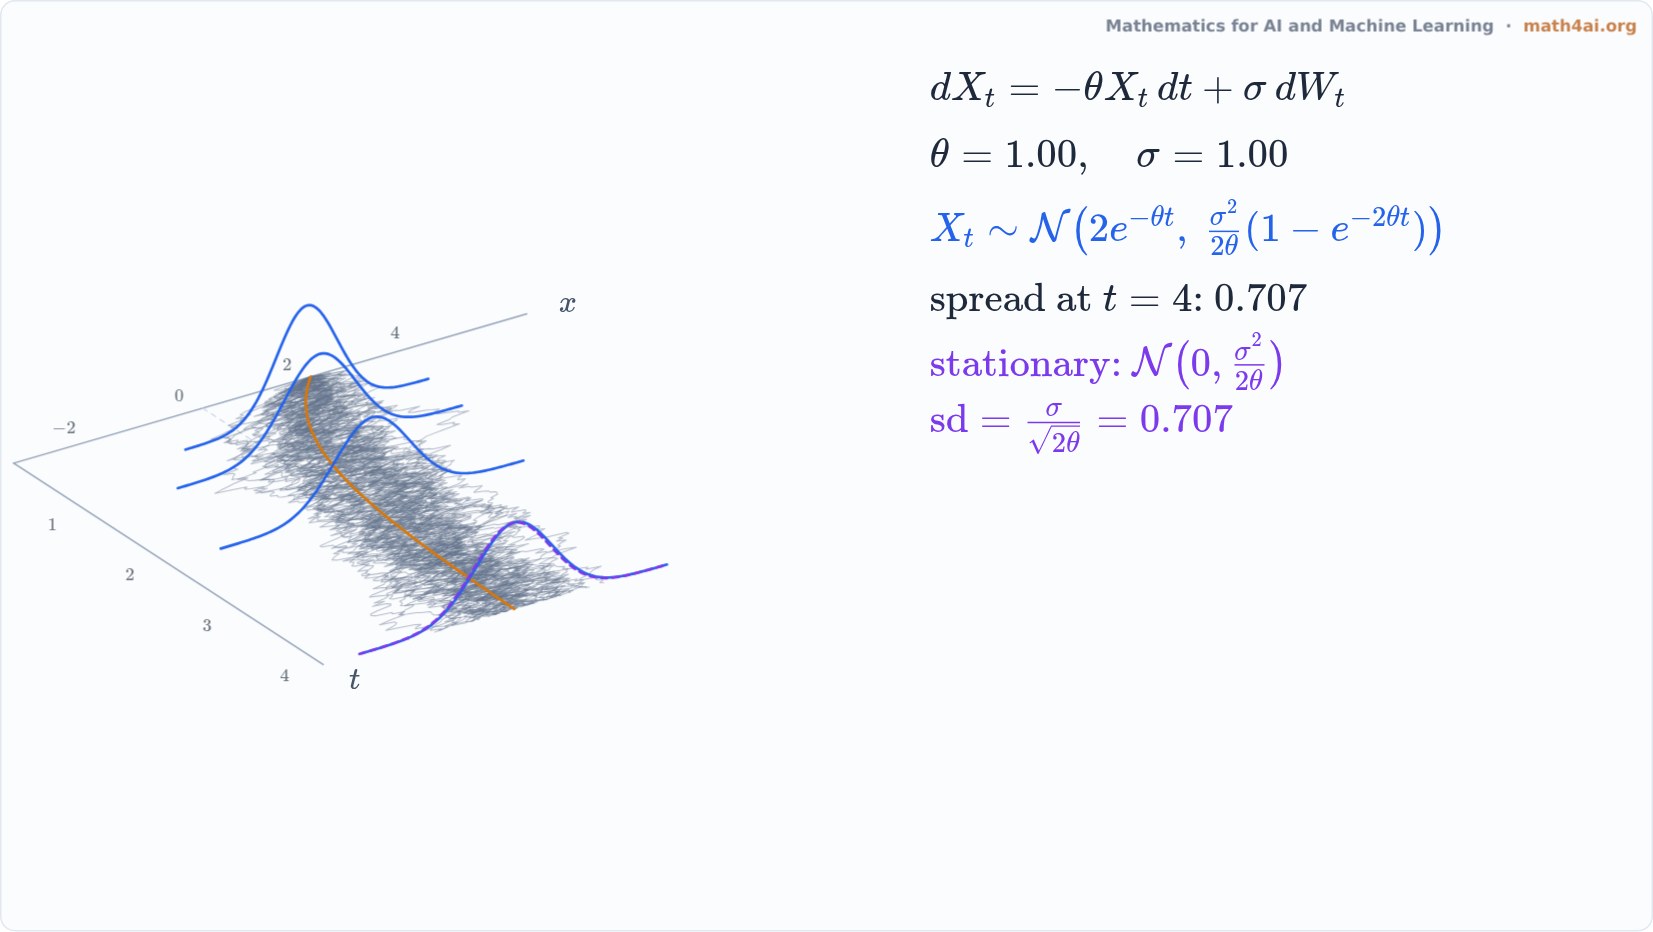 Preview1:17The Ornstein-Uhlenbeck Process: Brownian Motion on a SpringChapter 19
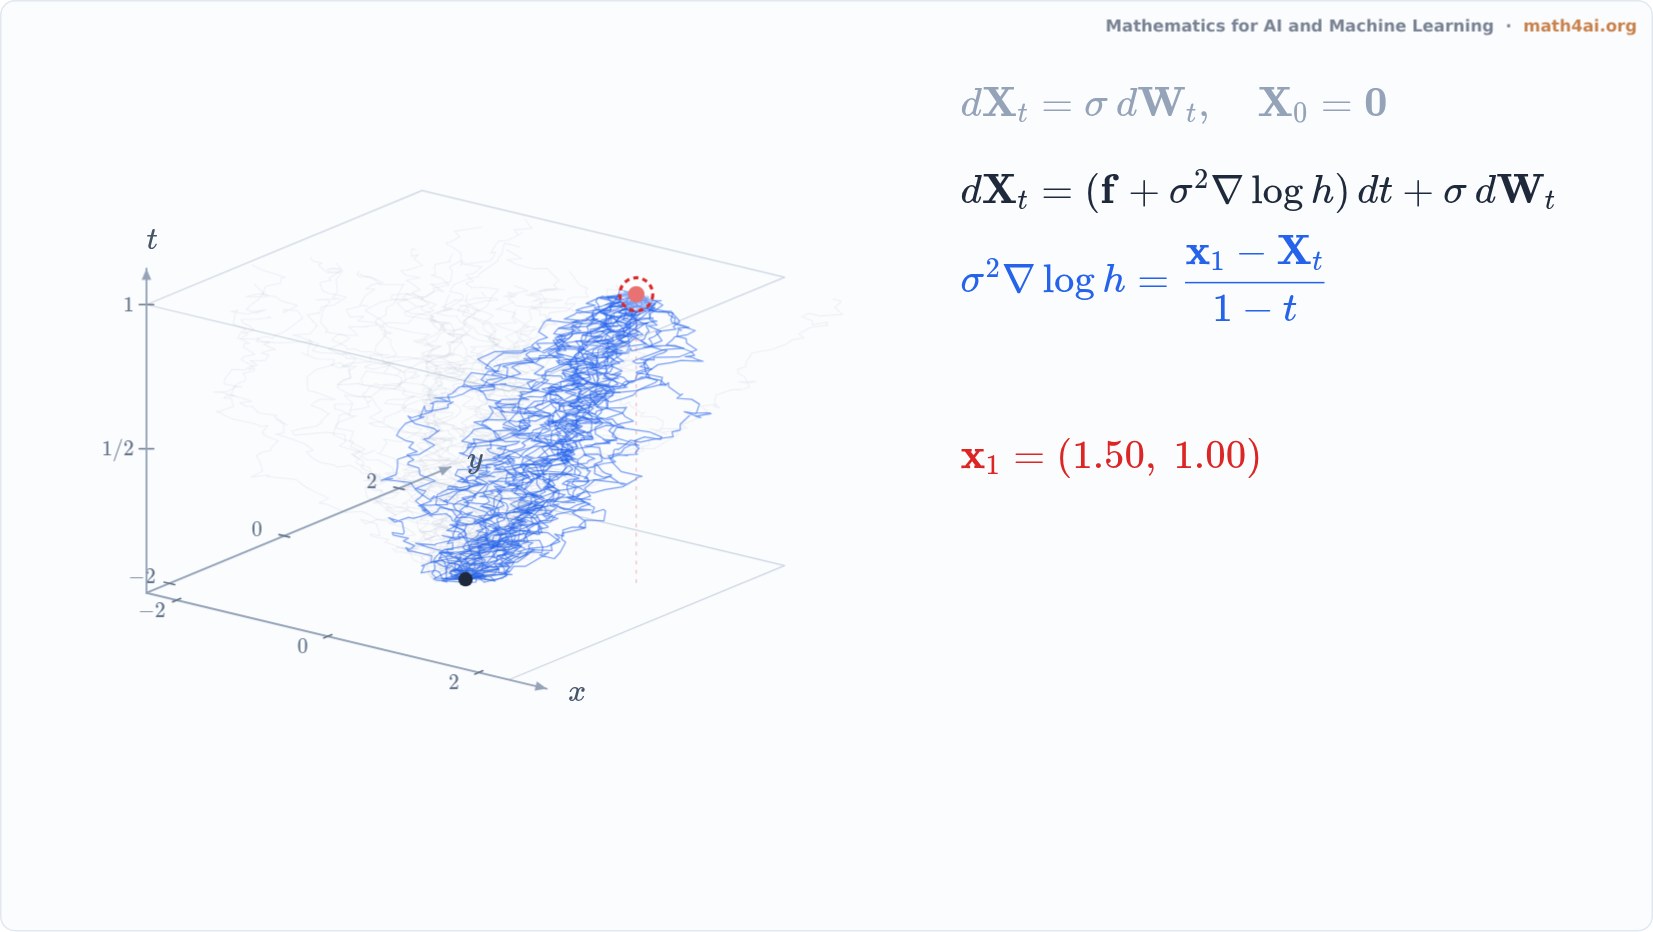 Preview1:29Conditioning a Diffusion on Its EndpointChapter 19
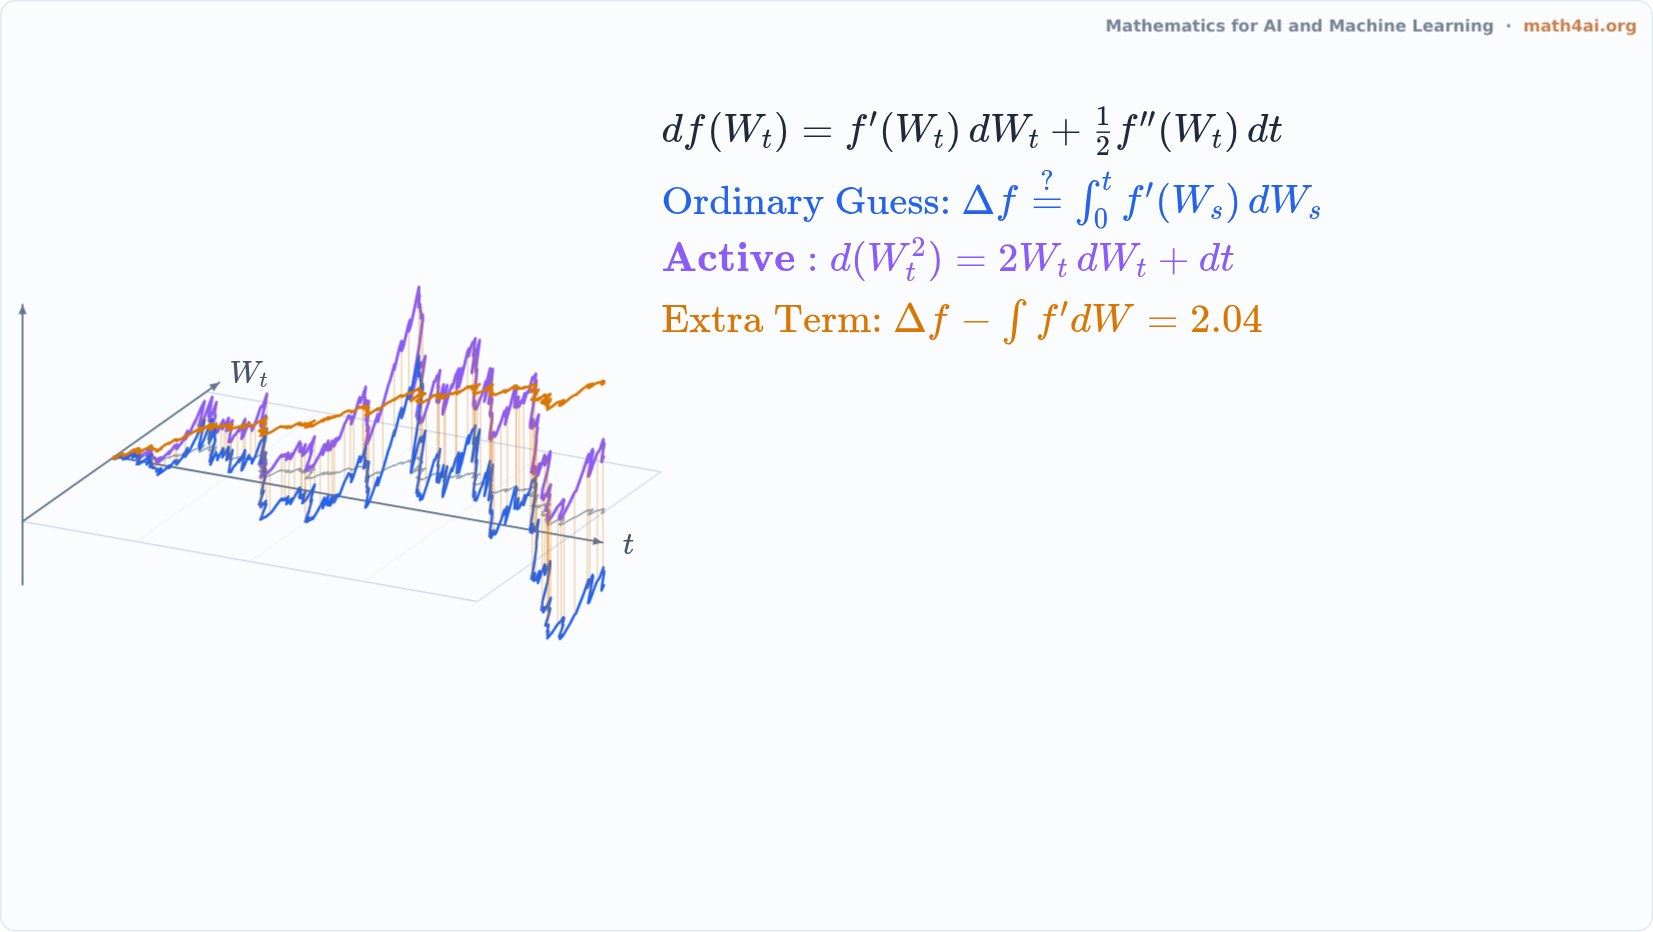 Preview2:01Itô's Lemma: The Extra Second-Order DriftChapter 19
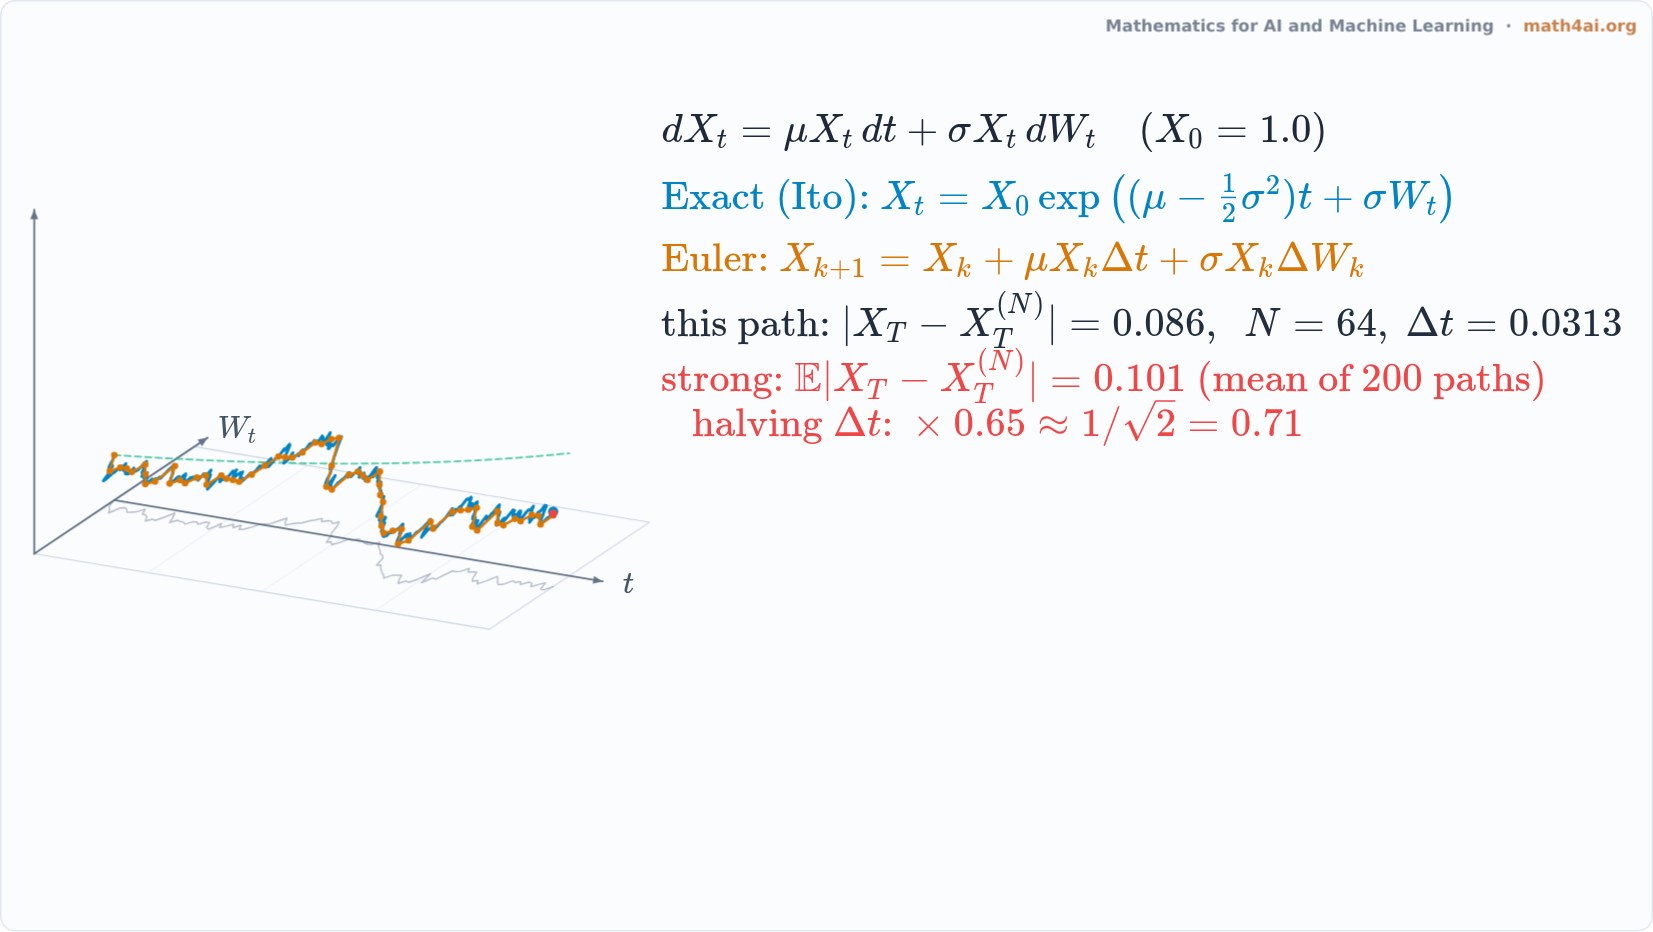 Preview1:56Euler–Maruyama: SDEs as Limits of AlgorithmsChapter 19