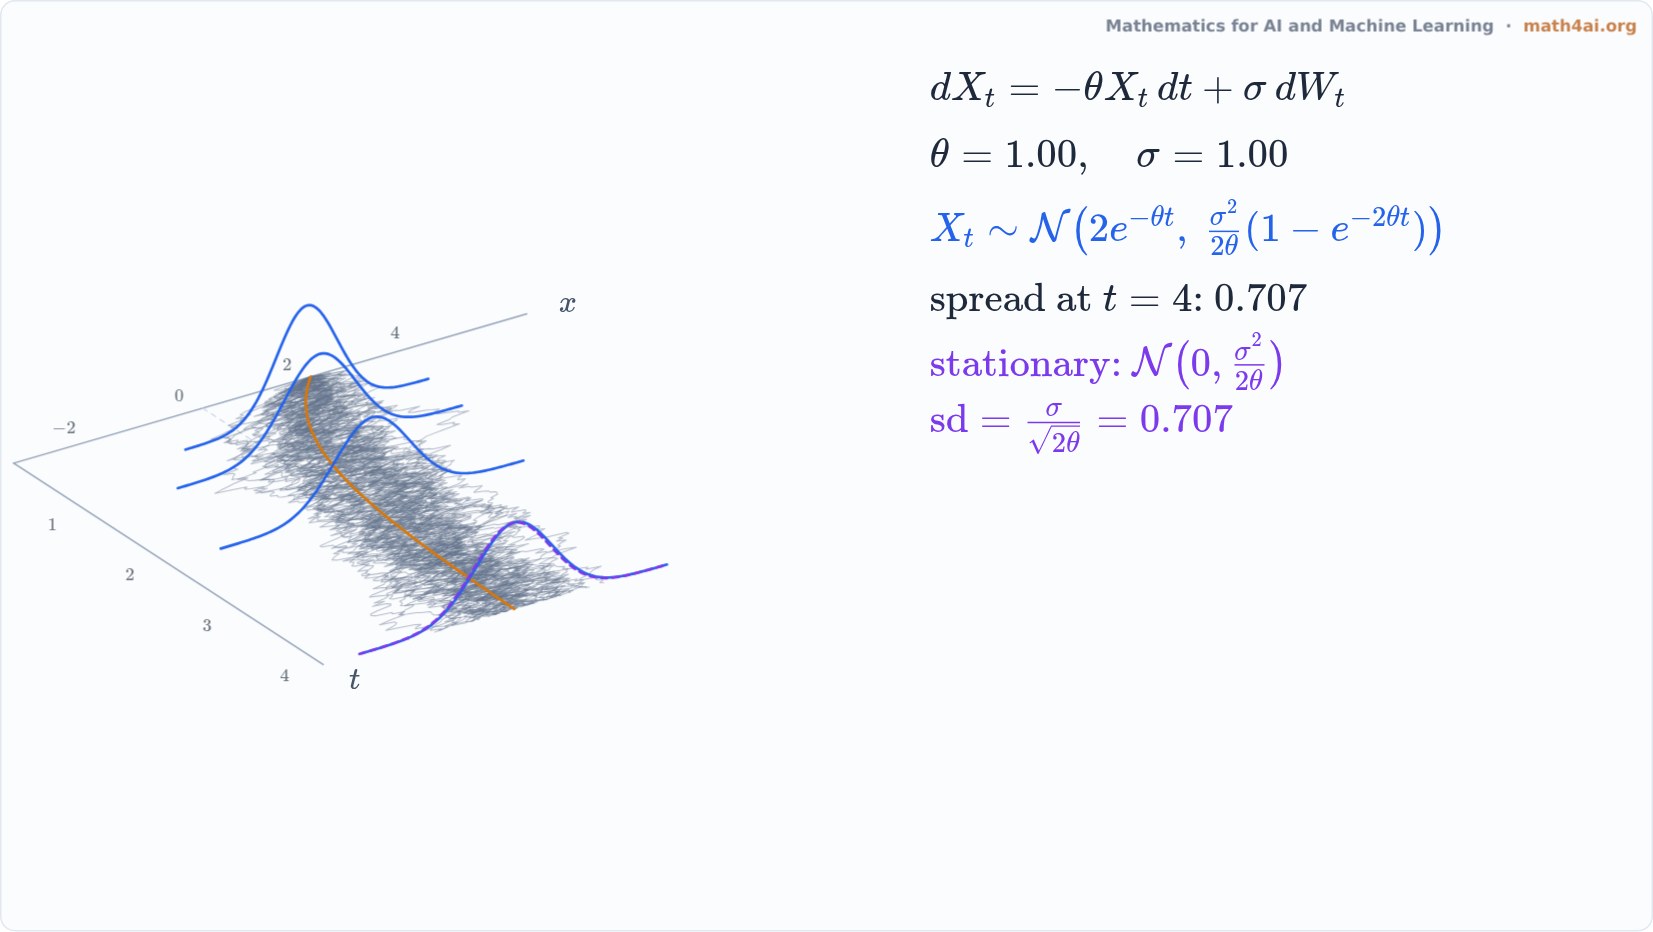
The Ornstein-Uhlenbeck Process: Brownian Motion on a Spring
An interactive live film: without a spring, Brownian paths spread forever; the drift −θx pulls them back, the mean decays and the bell settles into the stationary Gaussian with variance σ²/2θ. Roll the dice for new paths.
Narration
A crowd of particles starts at x equals two. Time runs along the floor, and each grey path is one particle.
With pure noise, Brownian motion, the cloud spreads forever: the blue bell keeps widening, like the square root of time.
The rest of the narration is in the book's Companion.
More from Chapter 19
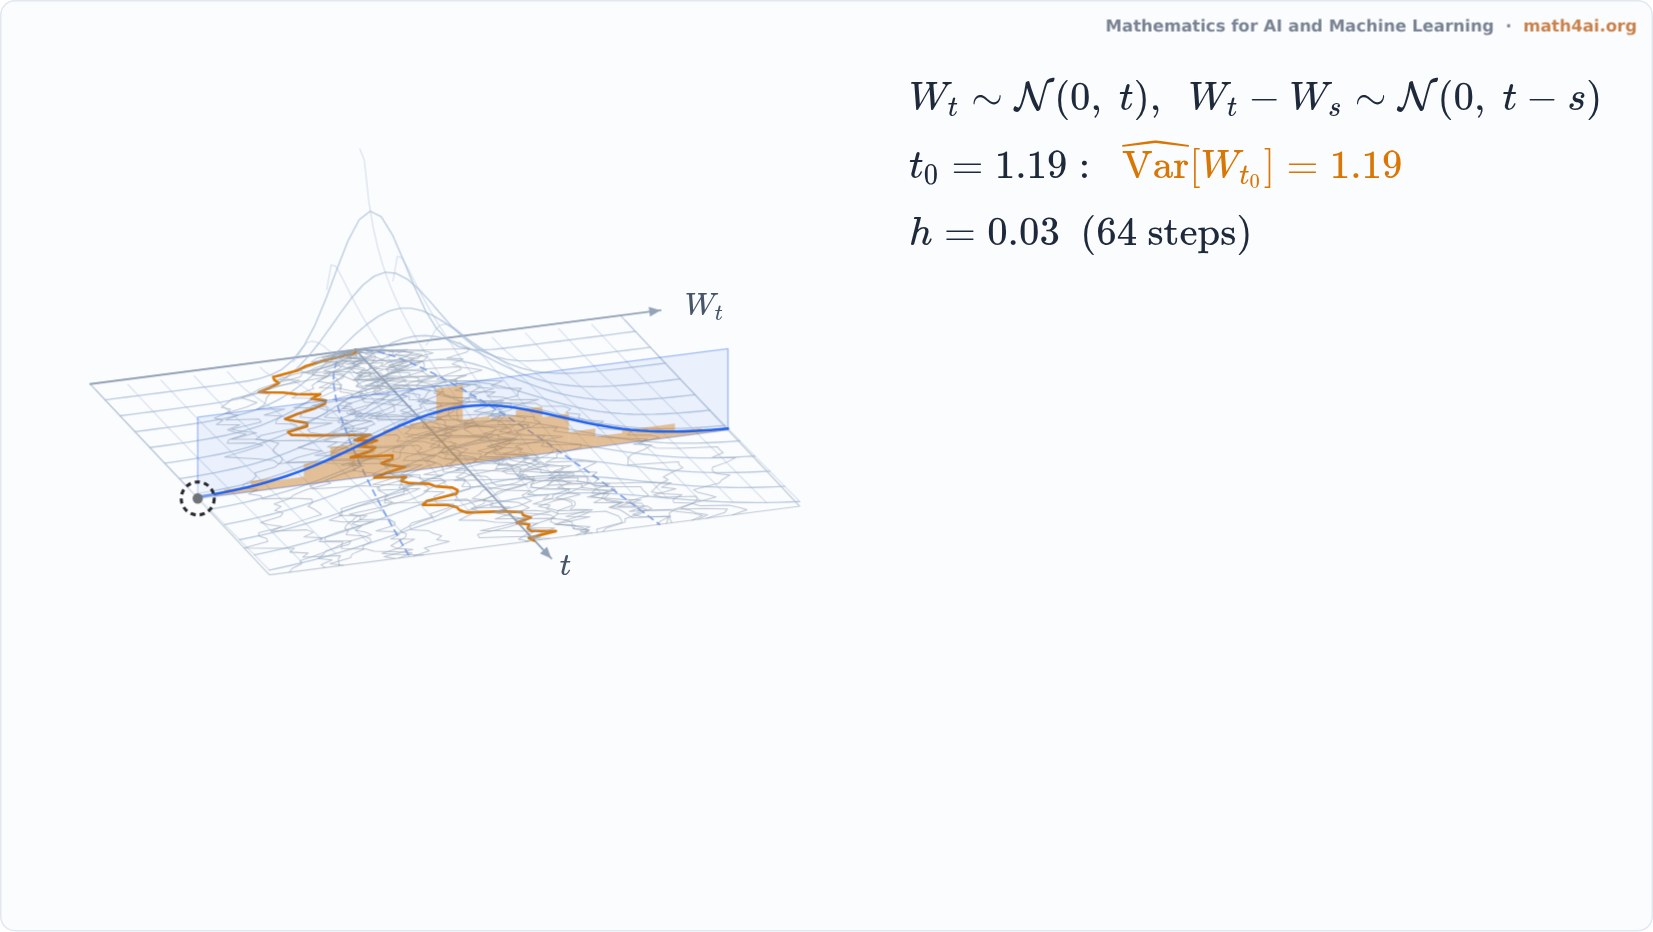 Interactive1:37Brownian Motion: Rough Paths, a Spreading Bell, and dW Squared Equals dtChapter 19
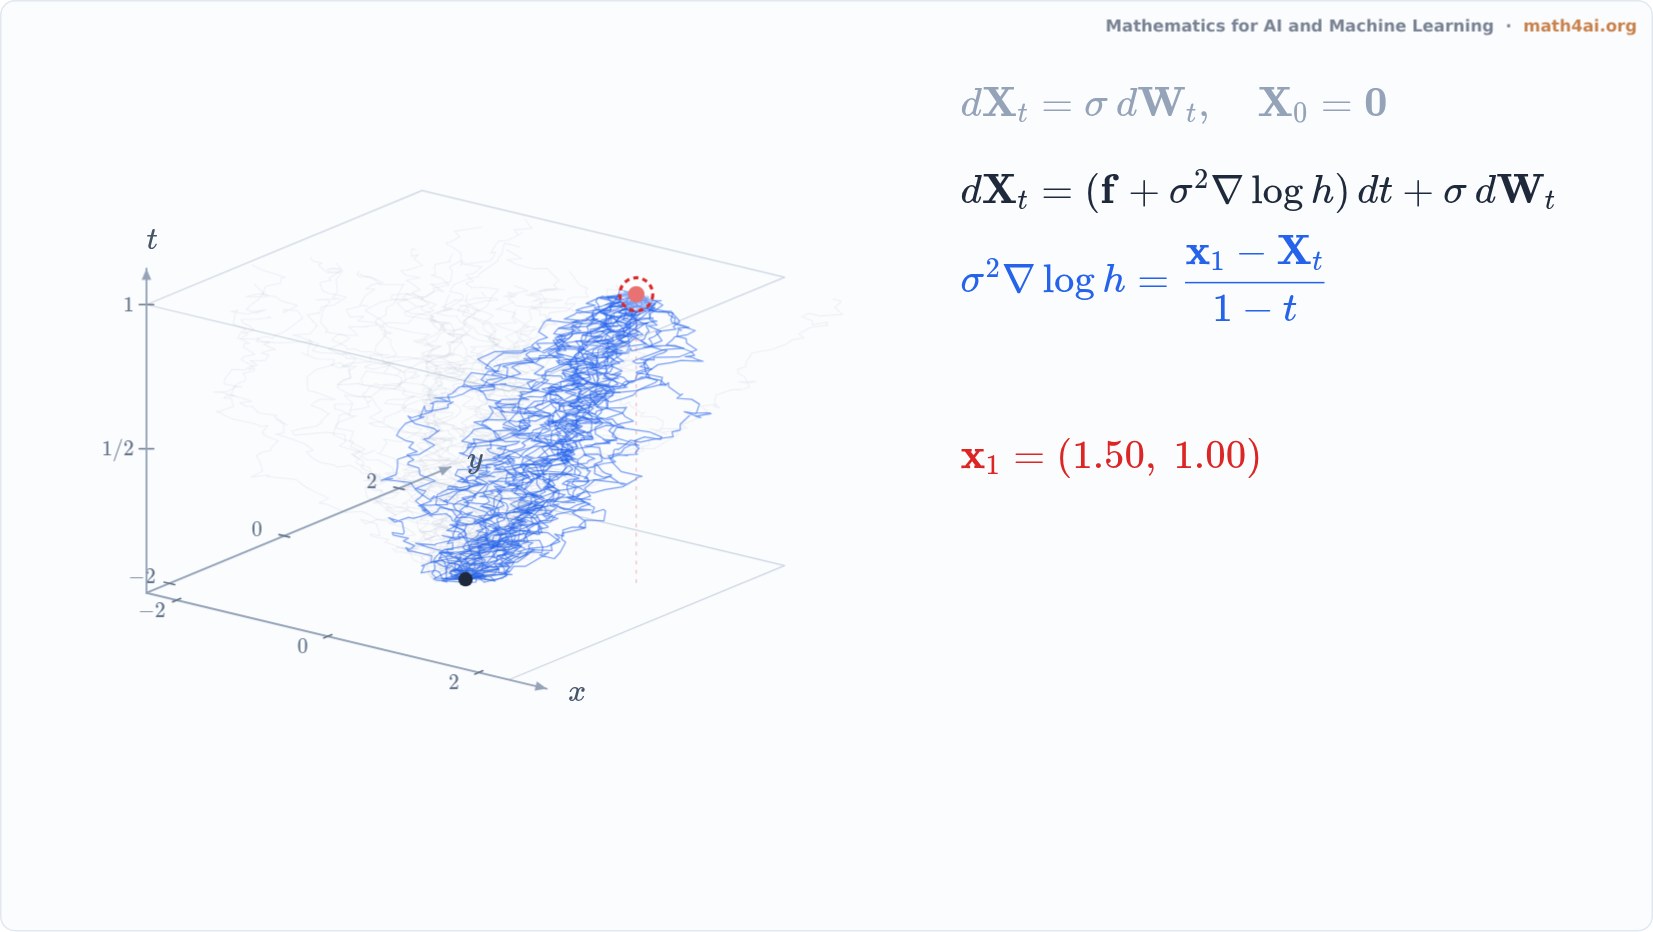 Preview1:29Conditioning a Diffusion on Its EndpointChapter 19
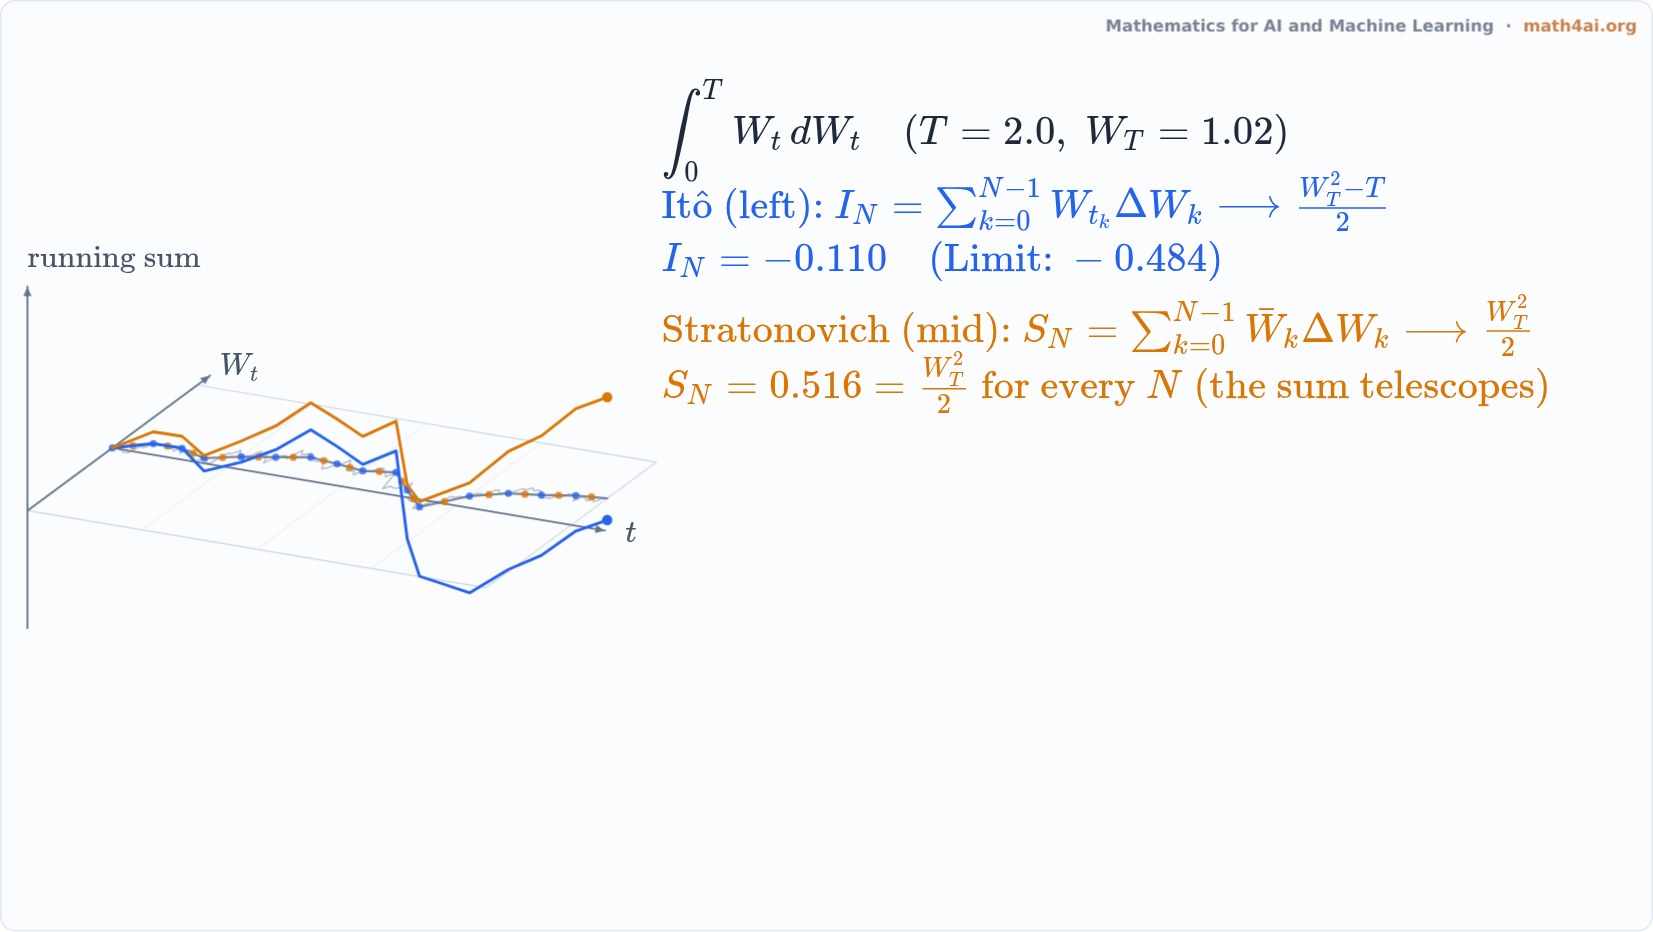 Preview1:46Itô vs Stratonovich: Left Endpoint or MidpointChapter 19
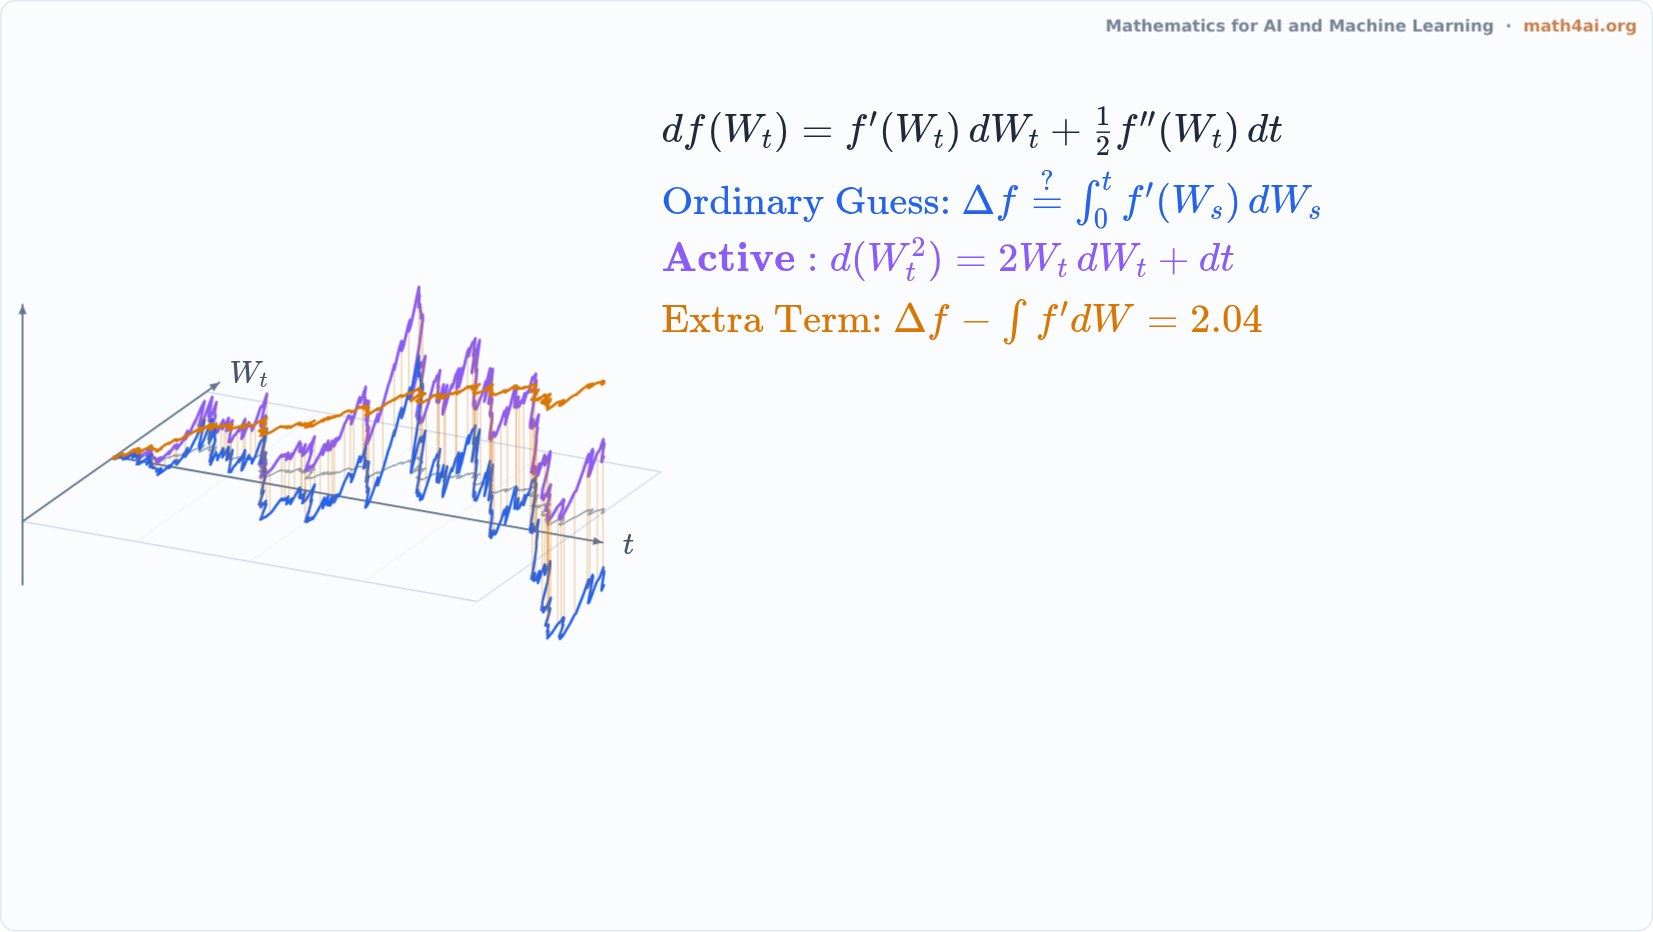 Preview2:01Itô's Lemma: The Extra Second-Order DriftChapter 19
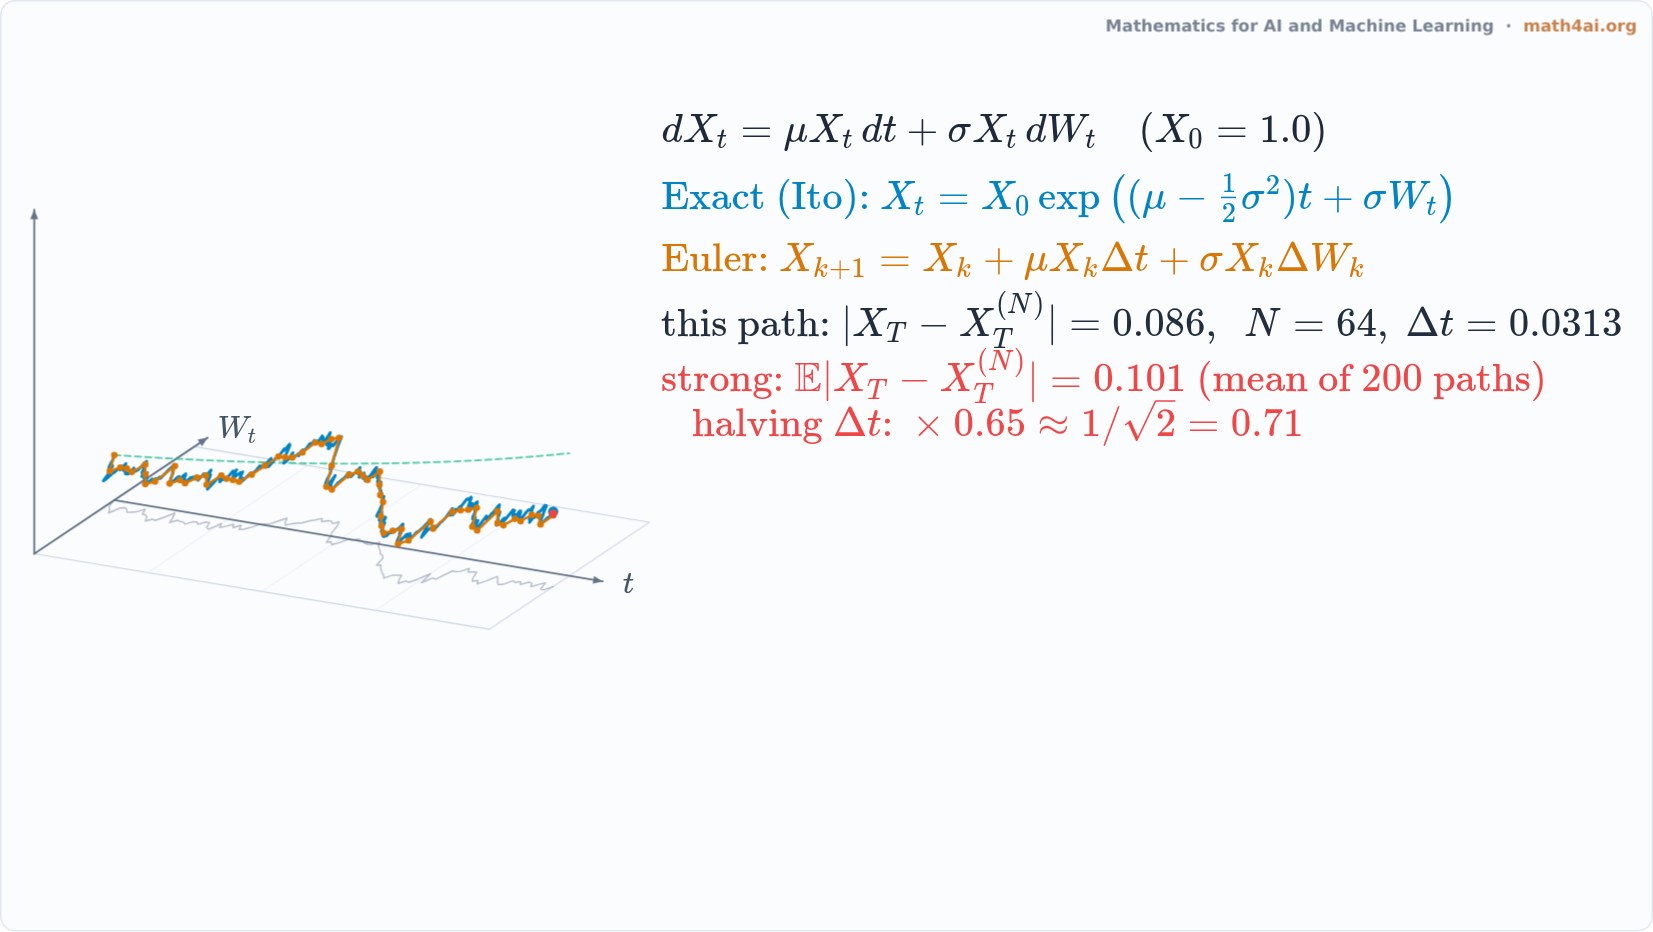 Preview1:56Euler–Maruyama: SDEs as Limits of AlgorithmsChapter 19