The Marchenko-Pastur Law and the Escaping Eigenvalue
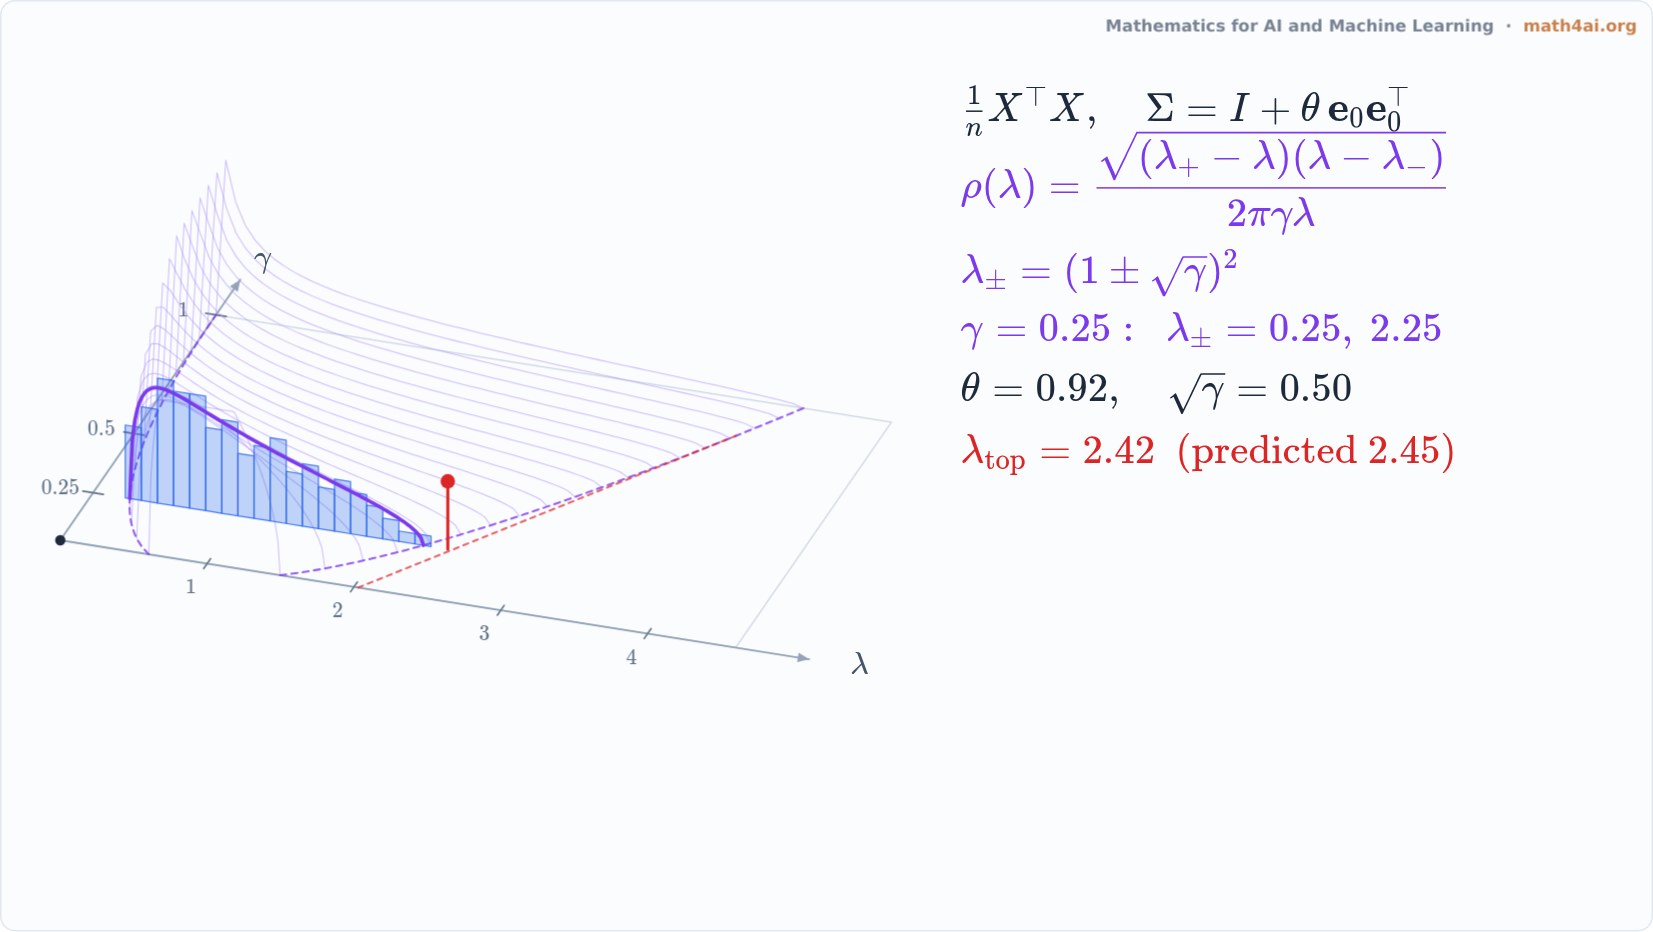
An interactive live film: sample covariance eigenvalues of pure noise spread over the Marchenko-Pastur bulk; plant a signal and find the threshold theta = sqrt(gamma) where its eigenvalue escapes.
Narration
Take n samples of p independent noise features, each with variance one, so the true covariance is the identity. Every eigenvalue of the sample covariance should then be close to one.
It is not. The blue bars are the sample eigenvalues for a ratio gamma of one quarter: they spread from one quarter to two and one quarter. The purple curve is the Marchenko Pastur law, which predicts this bulk.
The rest of the narration is in the book's Companion.
More from Chapter 8
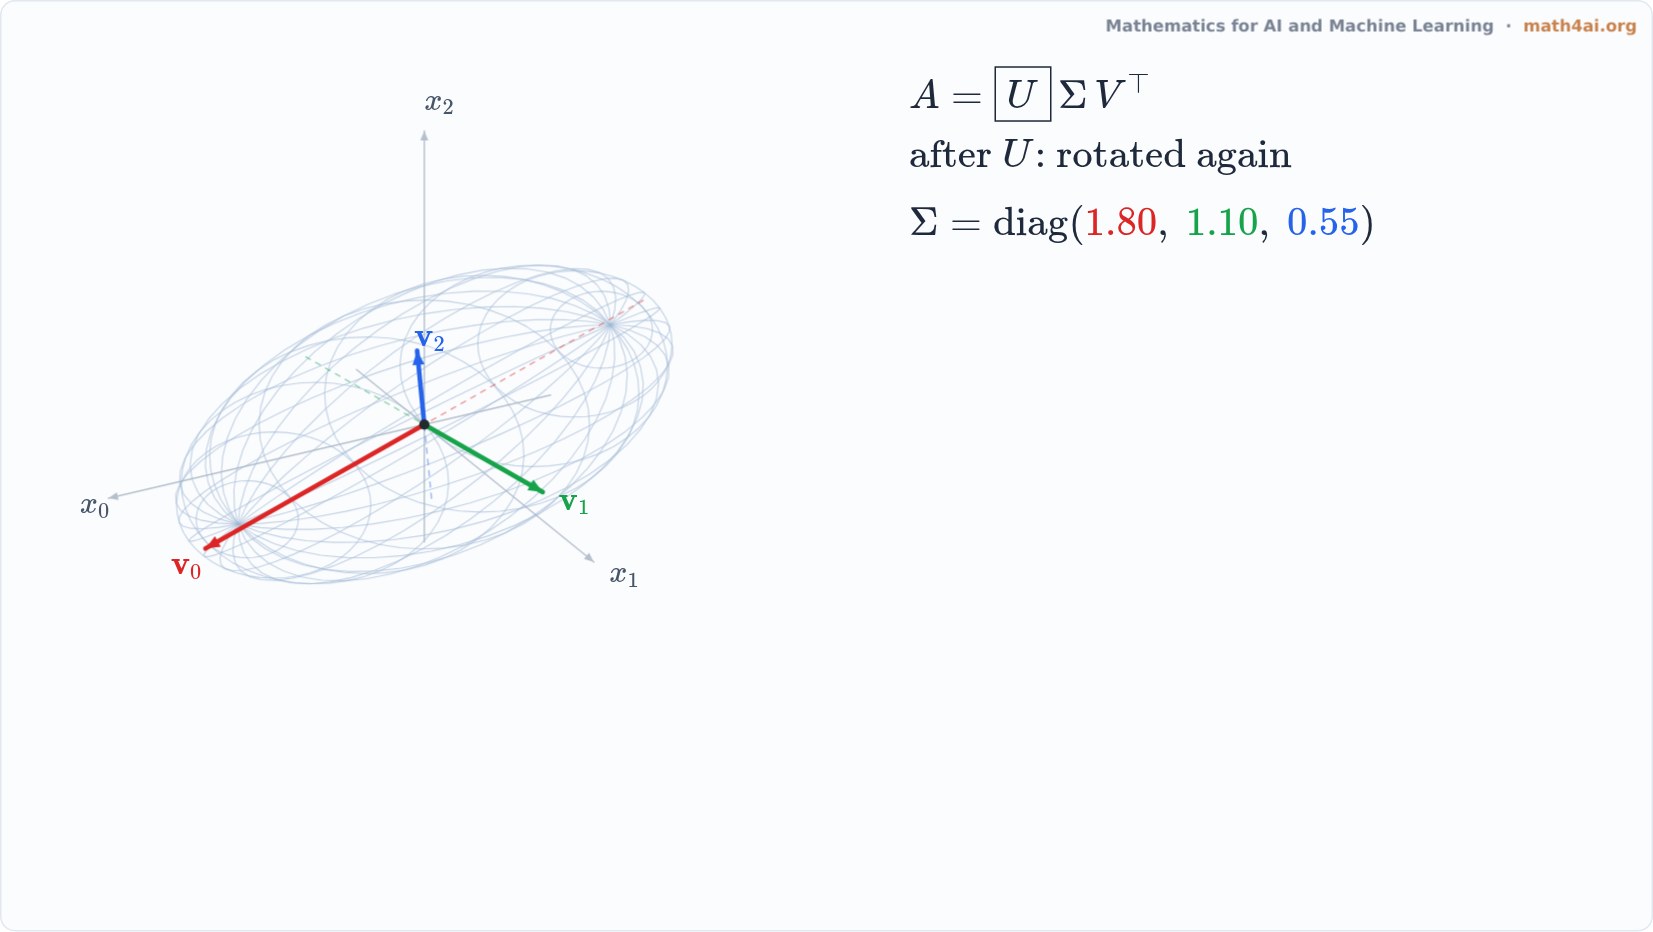 Interactive1:49SVD: Rotate, Stretch, RotateChapter 8
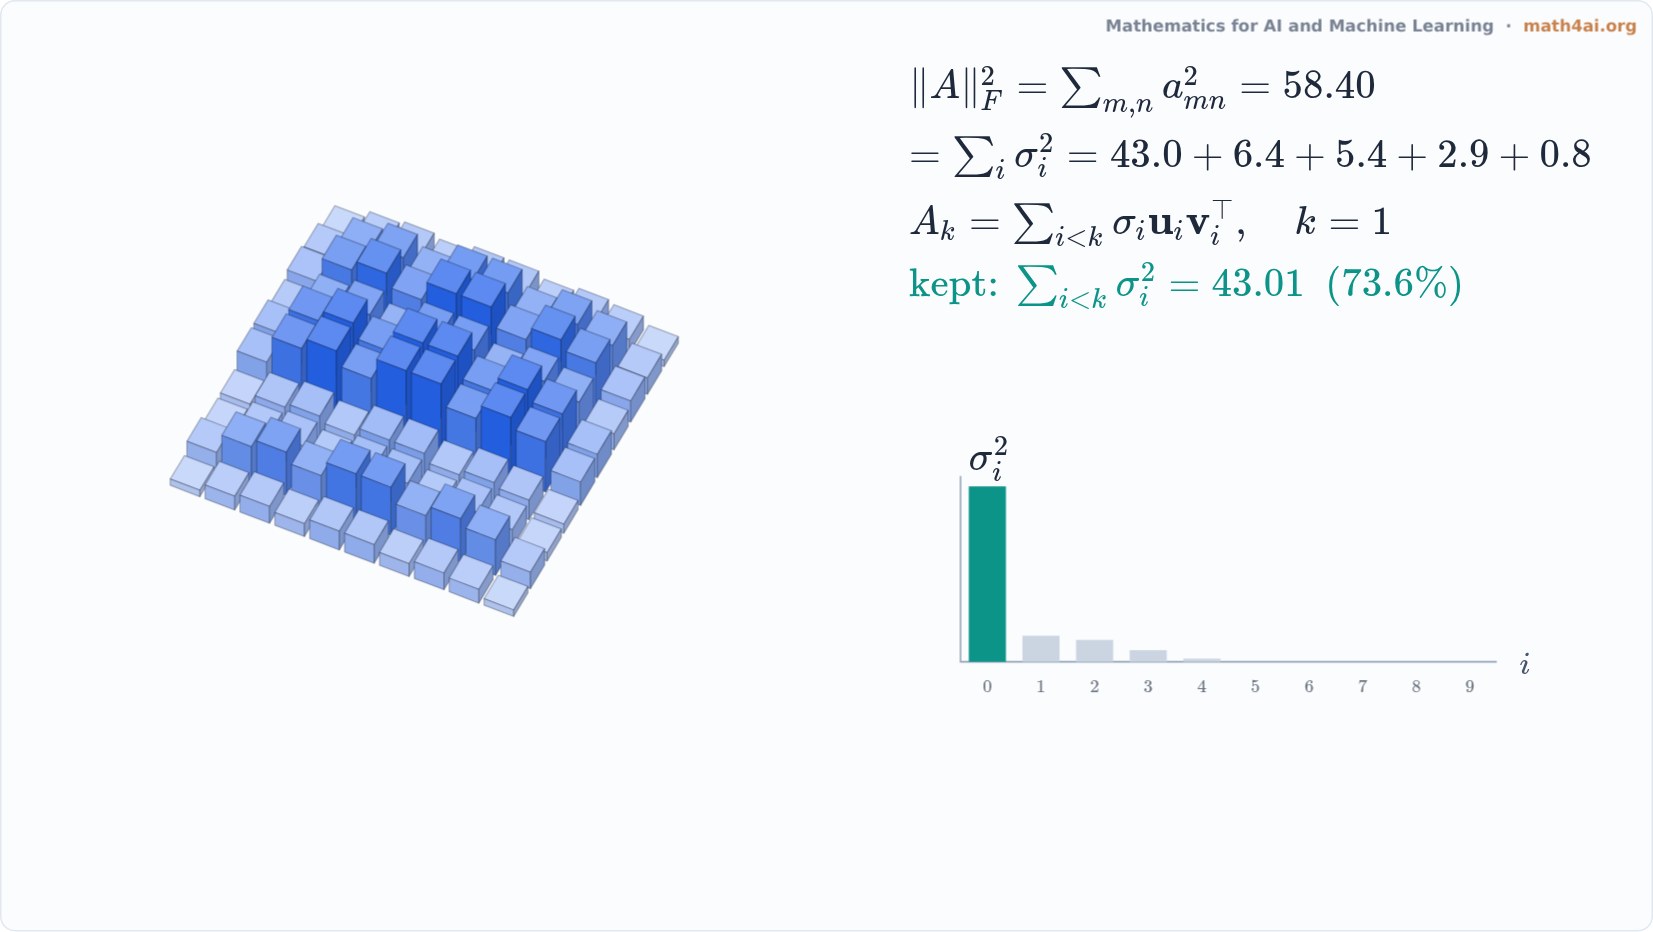 Preview1:31Energy from Singular Values: Rebuild a Picture Layer by LayerChapter 8
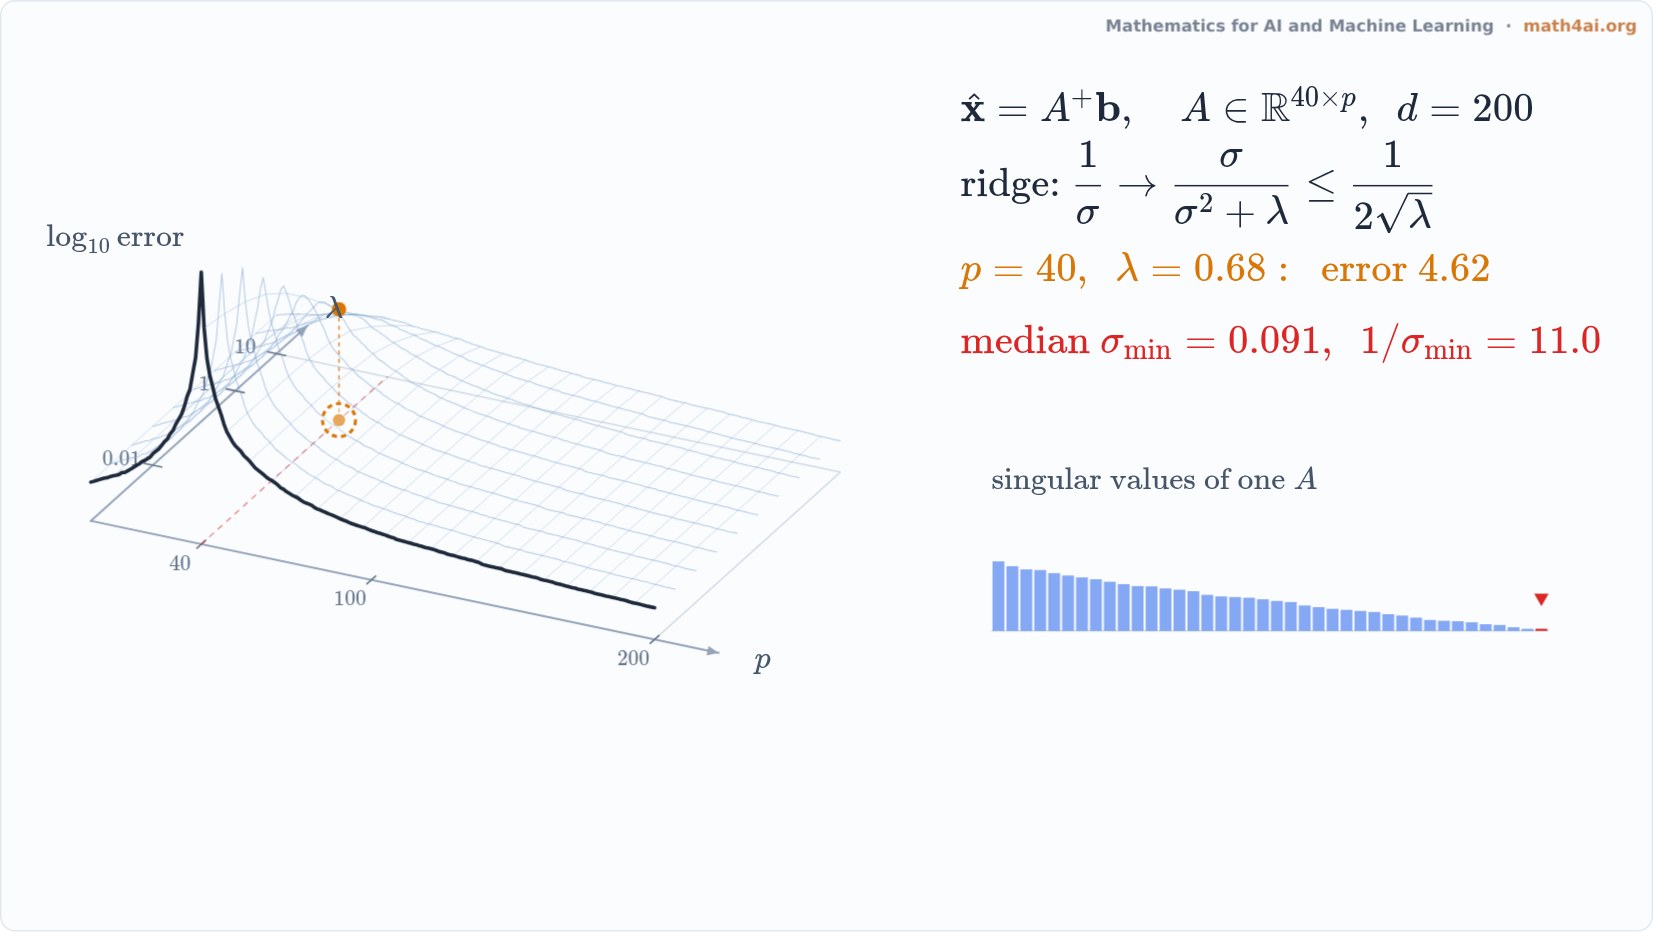 Preview1:33Double Descent at the Interpolation ThresholdChapter 8
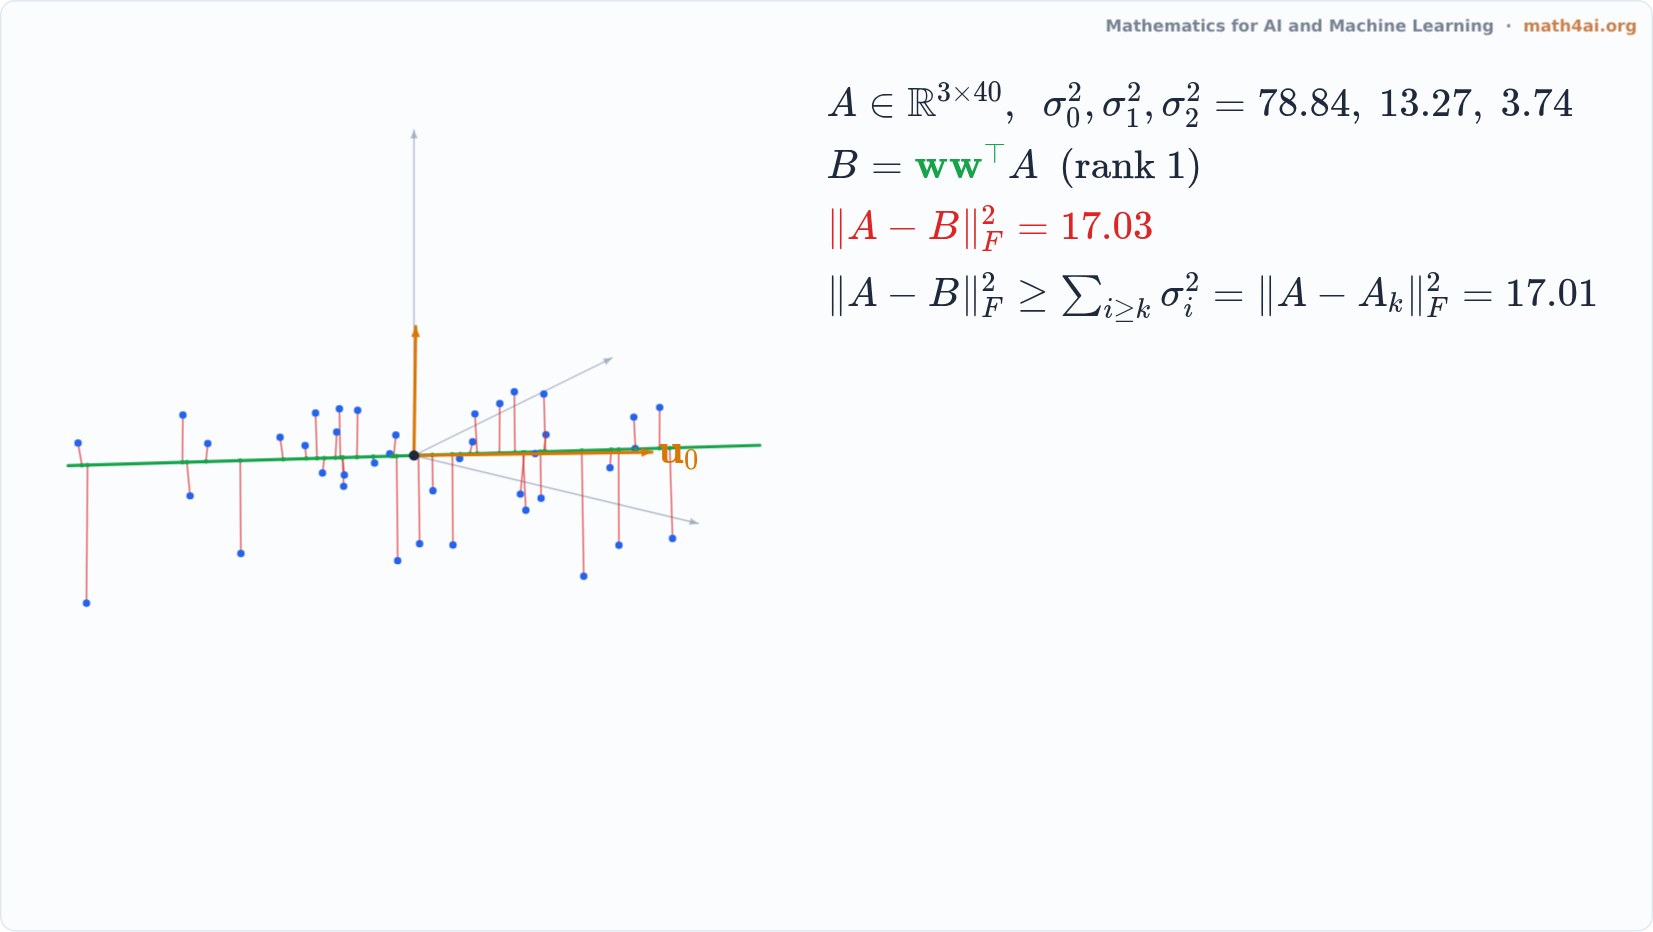 Preview1:43Eckart-Young: the Best Low-Rank ApproximationChapter 8
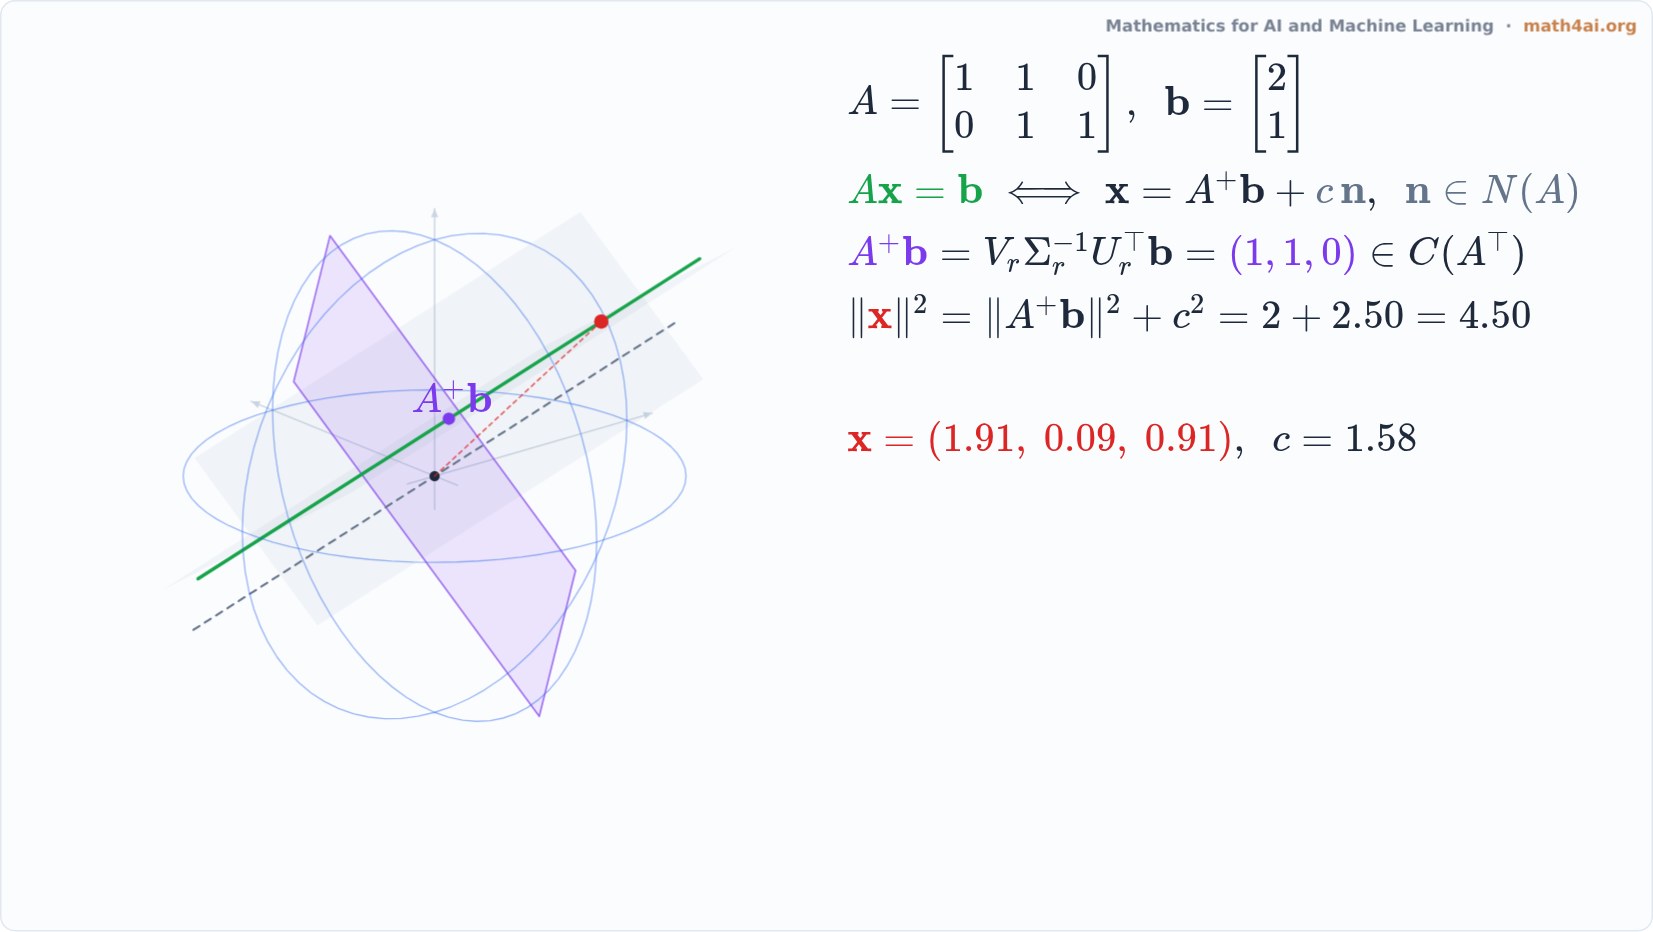 Preview1:46The Pseudoinverse: the Shortest SolutionChapter 8
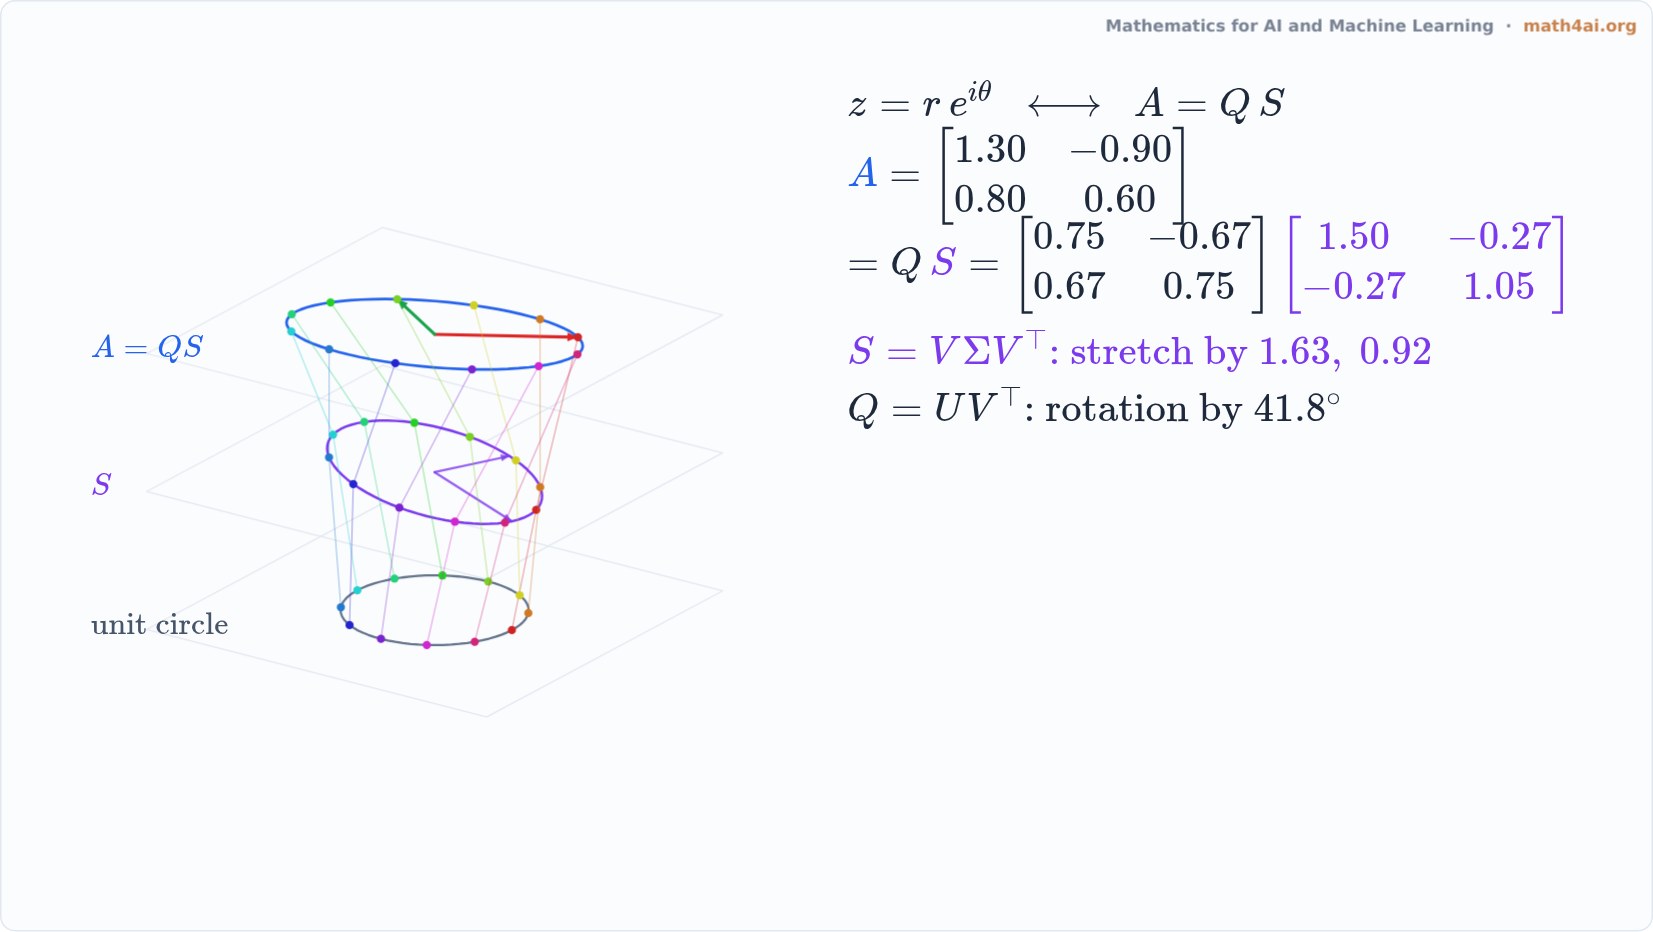 Preview1:31Polar Decomposition: Stretch, then RotateChapter 8
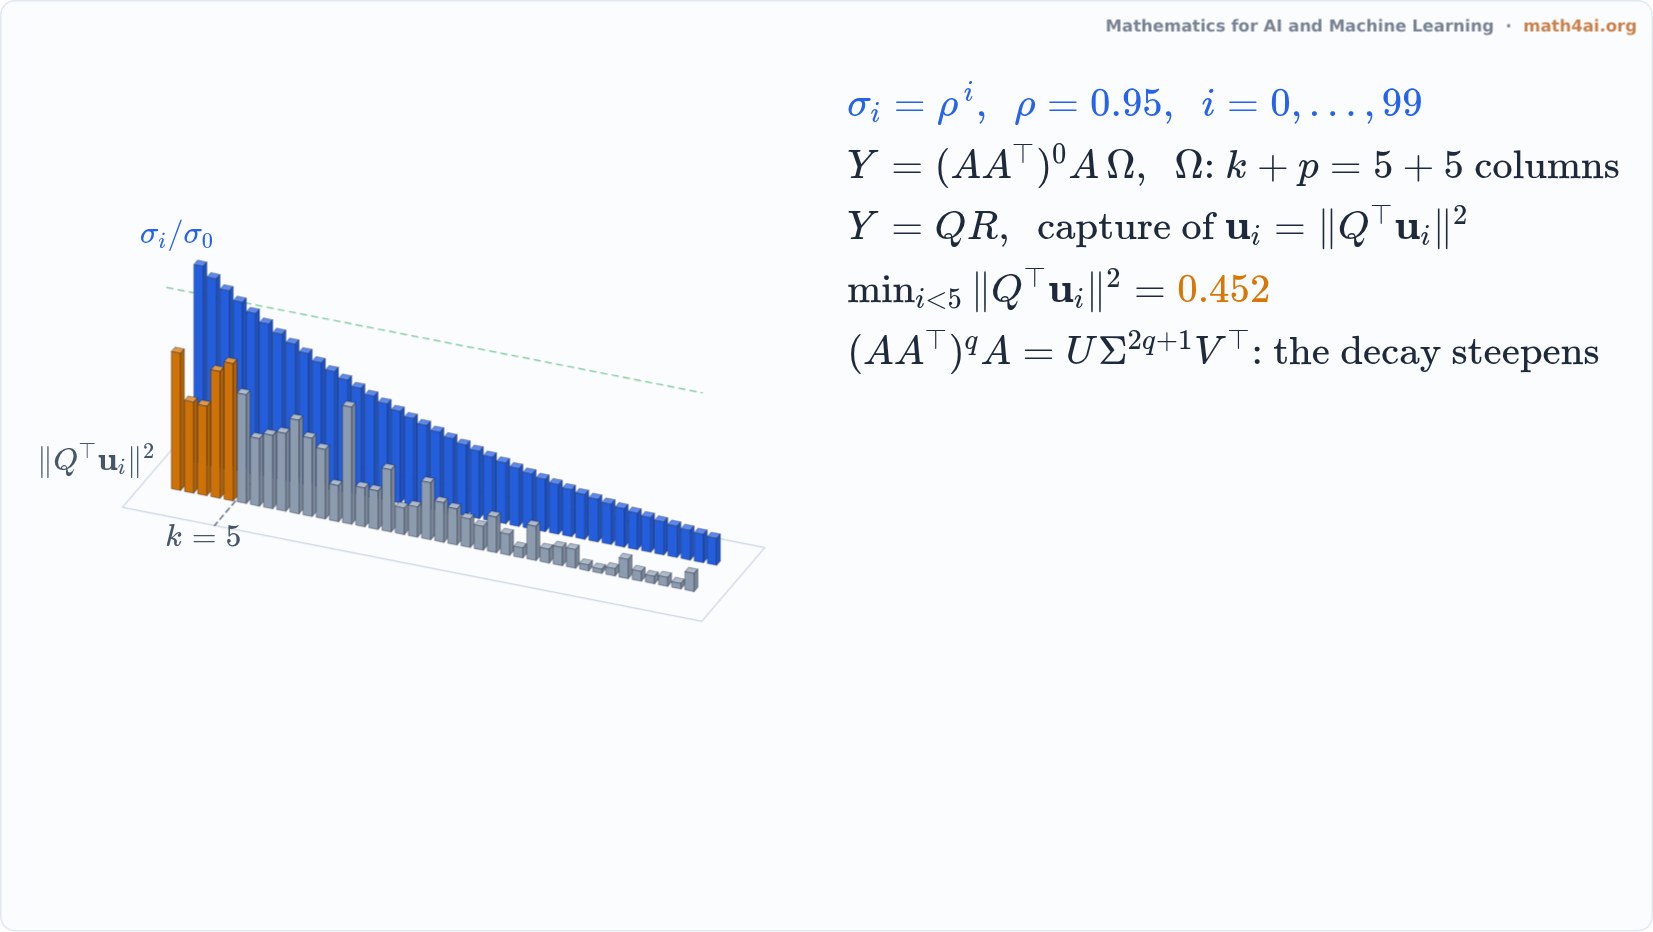 Preview1:47Randomized SVD: Catching the Top DirectionsChapter 8